Credit Hire When You Have a Loan Car From the Dealer
A dealer loan car is a short-term courtesy vehicle, not a credit hire replacement. It usually expires within days, often before your car is assessed, and it does not give you the same legal recovery rights as a like-for-like credit hire car.
If you were not at fault in a crash, you can generally recover the reasonable cost of a replacement vehicle that matches your own car's make, model and prestige from the at-fault insurer. But if you are still driving the dealer's loan car, you cannot double-dip. Knowing when to hand back the keys is the difference between a clean claim and a disputed one.
Key takeaways
- A dealer loan car is a short-term courtesy vehicle, not a credit hire replacement, and it usually expires within days.
- You cannot claim credit hire for any period when you already had the dealer loan car, because that would be double recovery.
- A like-for-like credit hire car matches your own car's make, model and prestige, and runs for as long as your car is genuinely off the road.
- Hand the dealer car back on the same day your credit hire car is delivered to avoid a gap and a disputed claim.
- Keep the dealer loan agreement, return docket and fuel receipts, because the at-fault insurer will ask for them.
- What a dealer loan car actually is
- When the dealer loan car runs out
- Why a like-for-like credit hire car is different
- What you can and cannot claim for the dealer car period
- Handing the dealer car back without a gap
- Paperwork to keep from the dealer
- When the at fault insurer questions the overlap
- Getting a prestige replacement the same day
What a dealer loan car actually is
A dealer loan car, sometimes called a courtesy car or service loaner, is a vehicle the dealership lends you while your own car is in their workshop. It is part of the service relationship, not part of the accident claim. The dealer owns it, insures it, and sets the rules: a kilometre cap, a fuel policy, a return date, and often a restriction that only the person named on the service booking may drive it.
In Sydney, most prestige dealers run a small fleet of loan cars from their service centres. If you bought your car from a dealership on the Pacific Highway at Artarmon or the Hume Highway at Warwick Farm, you might get a base model of the same brand for two or three days. It is a convenience, not a replacement. It does not have to match your car's specification, and the dealer can ask for it back whenever they need it for another customer.
Crucially, a dealer loan car is not provided under the credit hire system. Credit hire is a separate arrangement where a replacement vehicle is supplied to a not-at-fault driver on credit, and the cost is later recovered from the at-fault insurer. The dealer is not part of that chain, and the dealer's insurer is not going to chase the at-fault party for you.
If your car was damaged in a crash and is sitting at a dealer, the loan car they hand you is a bridging measure. It buys you a few days to sort out the claim. It does not settle your loss of use.
When the dealer loan car runs out
Dealer loan cars rarely last more than a few days. The service department needs them for the next booking. If your car is waiting on parts, the dealer may extend the loan once, but they are not obliged to. Once the repair is done, the loan car goes back immediately, even if you are still arguing with the insurer about who pays for what.
The gap usually opens up like this:
- Day 1: you drop your car at the dealer, they give you a loan car for 48 hours.
- Day 3: the dealer calls to say the car needs a new bumper bracket from Germany, six-week wait, and they need the loan car back tomorrow.
- Day 4: you are on the phone to the insurer, who tells you they will not authorise a hire car because they have not yet accepted liability.
That is the moment the dealer loan car stops being useful. You are not at fault, but you are about to be without a car for weeks. And the dealer is not going to fight the at-fault insurer on your behalf.
Some drivers try to keep the dealer car longer by delaying the return. That is a mistake. The dealer can report the car as unreturned, and you risk losing the goodwill you will need when your own car finally goes back in for the repair. Hand it back on time, and arrange a proper replacement through credit hire.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Why a like-for-like credit hire car is different
Credit hire is built around the legal principle of restitutio in integrum, which means putting you back in the position you would have been in if the accident had not happened. In New South Wales, the case of Arsalan v Rixon confirmed that a not-at-fault driver can recover the reasonable cost of hiring a replacement vehicle, even if they did not actually hire one, provided the replacement is like-for-like.
Like-for-like does not mean a Corolla because it has four wheels. If you drive a Range Rover Sport, a base hatchback is not a like-for-like replacement. The replacement should be comparable in make, model, age, condition and prestige. That is why credit hire providers specialise in prestige and performance vehicles.
Unlike a dealer loan car, a credit hire car is provided on a credit agreement. You sign paperwork that assigns the recovery rights to the credit hire company, and they pursue the at-fault insurer for the hire cost. You do not pay upfront. If the claim is accepted, the insurer pays. If it is disputed, the credit hire company typically wears the risk, provided you have been honest and followed the process.
The other difference is duration. A dealer loan car is measured in days. A credit hire car is provided for as long as your own car is genuinely off the road, including the assessment period, the parts wait, and the repair itself. That can be weeks or months for a prestige car with complex repairs.
If you want to understand the full mechanics, read our guide to how credit hire works. For a replacement that matches your car, you can book an accident replacement car in Sydney through Drive Tribe. This site is part of that group.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimWhat you can and cannot claim for the dealer car period
You cannot claim credit hire for a period when you already had the use of a dealer loan car. That would be double recovery. The at-fault insurer will reject any overlap immediately, and it makes the rest of your claim look opportunistic.
What you can claim for the dealer car period is narrower:
- Any excess kilometre charges or fuel costs you paid to the dealer, if they arose directly from the accident.
- Loss of use for days when the dealer car was not available, for example if the dealer took it back early and you had no replacement.
- Physical inconvenience or loss of amenity if the dealer car was materially inferior to your own car, such as a base model when you drive a performance vehicle.
What you cannot claim:
- The notional cost of the dealer loan car itself. The dealer provided it under your service agreement, not as a credit hire arrangement.
- Lost earnings for days when you had the dealer car and could still get to work.
- Any upgrade or additional insurance you chose to buy from the dealer.
Keep the dealer's loan agreement and any receipts. They establish the exact dates you had the car, which is the evidence you need to show there was no gap and no overlap. If the dealer charged you for fuel or a cleaning fee, that is a small out-of-pocket loss that can be included in your claim.
For a fuller breakdown of what is recoverable, see credit hire costs and who pays what.
Handing the dealer car back without a gap
The cleanest handover is same-day: you return the dealer car in the morning and collect the credit hire replacement in the afternoon. That way there is no period where you are without a car, and no argument about whether you mitigated your loss.
Plan it in this order:
- Get the dealer's return date in writing. An email or text is fine.
- Confirm with the credit hire provider that your replacement is ready and the paperwork is signed.
- Arrange delivery to the dealer's service centre or your home or office. In Sydney, delivery is available across the metro area, including the CBD, Parramatta, Chatswood, Sutherland and Penrith.
- Photograph the dealer car's fuel gauge and odometer before you hand back the keys.
- Get a receipt or return docket from the dealer.
If the dealer car runs out before your credit hire car is ready, do not panic. You can still claim loss of use for the gap, but it is easier to avoid the gap entirely. Tell the credit hire provider your return date as soon as you know it. They can usually line up a replacement within 24 hours, and often the same day if you are in the eastern suburbs or inner west.
If you are not sure what you are signing, read what you sign in credit hire paperwork before you commit.
Paperwork to keep from the dealer
Your credit hire claim will be assessed on documents. The at-fault insurer will ask for proof of the dates you had the dealer car, the dates you had the credit hire car, and confirmation that there was no overlap. Missing paperwork is the most common reason a claim gets delayed.
Keep these:
- The dealer loan car agreement, signed and dated.
- The return docket or email confirming the car was handed back.
- Any fuel or cleaning receipts you paid.
- The service invoice showing your own car was in the dealer's workshop.
- Photos of the dealer car's dashboard, showing fuel level and odometer, on the day you collected it and the day you returned it.
- Correspondence with the dealer about extending or returning the car.
Store them in one folder, digital or physical. If the insurer disputes the overlap, you can produce a clean timeline in minutes rather than days. That alone can shorten the settlement.
If you have already lost the paperwork, ask the dealer for a copy. Service departments keep records. A short email to the service manager usually gets a PDF back the same day. If the dealer has closed or changed hands, your bank statement showing the fuel purchase can help establish the date.
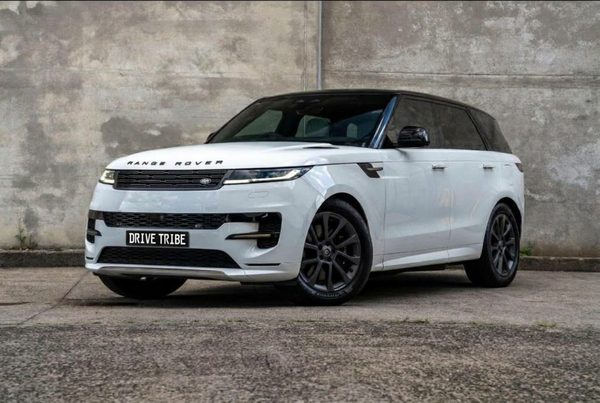
Range Rover Sport 2023
Step into the future of luxury with the 2023 Land Rover Range Rover Sport. Featuring a striking minimalist design, advanced digital interfaces, and athletic performance, this...
When the at fault insurer questions the overlap
Insurers are trained to look for double recovery. If they see a dealer loan car and a credit hire car running at the same time, they will write to you and ask for an explanation. Sometimes it is a genuine overlap of a day or two because the dealer car was returned late or the credit hire car was delivered early. Sometimes it is an administrative error on the claim form.
How to respond:
- Do not ignore the letter. A failure to respond is treated as an admission.
- Send the dealer loan agreement and the return docket, showing the exact return date.
- Send the credit hire agreement and the delivery docket, showing the exact start date.
- If there is a one-day overlap, explain it plainly and offer to reduce the claim by that day's hire cost.
- If the insurer still disputes, the credit hire company will usually handle the argument. That is part of what you signed up for.
Most disputes are resolved at this stage. If yours is not, read when an insurer disputes a credit hire claim for the next steps.
One more thing: if the dealer loan car was materially better than your own car, do not mention it as a reason to reduce your claim. The test is what you lost, not what you borrowed. A dealer's top-spec demo does not cancel your right to a like-for-like replacement for your own car.
Getting a prestige replacement the same day
In Sydney, same-day replacement is realistic if you call early. Most credit hire providers keep a pool of prestige cars at Mascot, near the airport, and can deliver to the dealer, your home or your office. If you are in the CBD, Surry Hills, Bondi or North Sydney, a morning call usually means an afternoon delivery.
What you need ready:
- Your driver's licence.
- The other driver's details, including their insurer if you have it.
- Photos of the damage to both cars.
- The police event number, if you reported it.
- The dealer's return date for the loan car.
Then choose a replacement that matches your own car. If your car is a large luxury SUV, a Range Rover Sport is a natural like-for-like. If you drive a performance SUV, a Porsche Macan fits the same brief. If your car is a long-wheelbase luxury sedan, a Mercedes-Benz S500 L is the closest match.
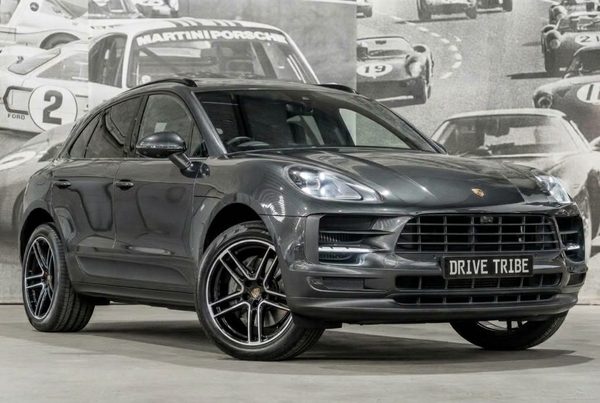
Porsche MACAN
2019 Porsche MACAN...
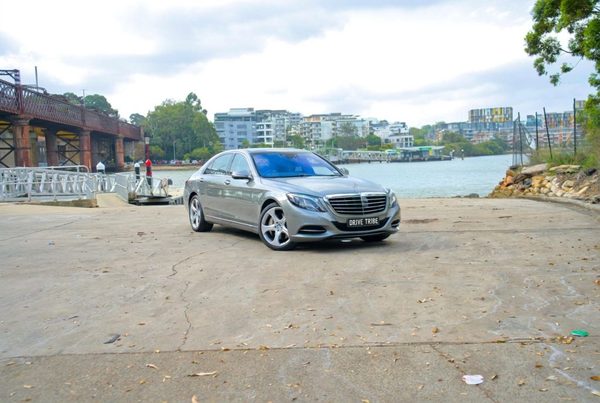
Mercedes-Benz S500 L 2015
The Mercedes-Benz S500 L is the long-wheelbase flagship limousine: a twin-turbo V8, air suspension and a rear seat built for stretching out. For a wedding, a milestone or simply...
Delivery is available across the metro area. Minimum driver age is 20 on most cars, though some are 25 or 30. The rate, the bond and any fees are shown on the car's page before you pay. You can pay by card, which carries a small surcharge, or by bank transfer or cash on the rental, which do not. Bookings can be from a single day.
To start the process, arrange a not-at-fault replacement car and have your dealer return date ready. If you want to understand the loss-of-use side, see loss of use, physical inconvenience and loss of amenity.
Questions people ask
Can I claim credit hire if the dealer already gave me a loan car?
Does the dealer loan car affect my loss of use claim?
How quickly can a replacement car be delivered in Sydney?
What if the dealer loan car was a better car than mine?
Do I have to tell the at-fault insurer about the dealer loan car?
Can I keep the dealer loan car until my credit hire car arrives?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe.
Start my claim