Insurer Write-Off Offers and Your Replacement Car
If your prestige car is written off after a not at fault accident, the insurer's cash settlement offer is rarely the end of the story. You are entitled to be put back in the position you were in before the crash, and that includes a replacement car while you decide what to do.
This guide explains how insurers decide between repair and write-off, how to read a settlement offer properly, why prestige cars are often undervalued, and how long you can keep a like-for-like replacement while you negotiate and buy again.
Key takeaways
- A write-off settlement and your replacement car claim are separate: you can negotiate the money while keeping a like-for-like hire car.
- Insurers often undervalue prestige cars because guide books miss options, service history, and low kilometres.
- You are entitled to a replacement car for a reasonable period while you decide on the offer and buy again.
- Do not accept a low offer or return the hire car to speed things up; gather evidence and counter in writing.
- If the insurer will not move, escalate to AFCA, but keep the replacement car claim running.
- How insurers decide between repair and write-off
- Reading a cash settlement offer properly
- Why prestige cars are often undervalued in offers
- Your entitlement to a replacement while you decide
- How long you can keep the hire after a write-off
- Negotiating the settlement without losing the hire claim
- Buying your next car: timing and finance
- What to do if the offer is clearly too low
- The first 24 hours after a write-off decision
How insurers decide between repair and write-off
An insurer will write off your car when the cost of repairing it, plus the salvage value, exceeds its assessed market value. That is the economic test, and it is applied by an assessor who may never see the car in person. In NSW, a write-off is also a legal status: once an insurer declares your vehicle a statutory write-off, it cannot be re-registered, regardless of how well it could be repaired.
The decision usually comes down to a repair estimate from a smash repairer, often one on the insurer's preferred list. For a prestige car, that estimate can climb quickly. A Porsche 911 with rear quarter damage may need a jig, aluminium panel work, and recalibration of driver-assistance sensors. A BMW M3 with front-end damage can need new radar and camera modules, plus a genuine bonnet and bumper. Parts alone can run into tens of thousands before labour.
Insurers also consider the salvage value. A written-off Range Rover Sport may still fetch a strong price at auction for its drivetrain and interior. If the salvage value plus repair cost crosses the threshold, the insurer writes it off and pays you the market value instead.
You are not obliged to accept the insurer's first repair estimate or its preferred repairer. If you believe the car is repairable and you want it repaired, you can obtain your own quotes from a specialist. But be aware that once a write-off is recorded, the clock is ticking on your options.
Reading a cash settlement offer properly
A cash settlement offer is not just a number. It is a package that includes the assessed value of your car, minus any excess, plus any adjustments for registration, CTP, and remaining finance. Read it line by line, because the headline figure can hide deductions.
Start with the assessed market value. Ask the insurer for the valuation report or the comparable sales it used. For a prestige car, a single online guide is not enough. The insurer should be able to show you actual sales of similar cars, with similar kilometres, options, and service history, within the last few months. If the comparables are from interstate or from a different trim level, challenge them.
Next, check the deductions. These can include:
- Your policy excess, which may not apply if you are not at fault and the other driver is identified.
- Remaining registration and CTP, which should be refunded or transferred, not swallowed.
- Finance payout, which is paid directly to your lender.
- Any aftermarket accessories you declared, such as a tow bar, roof racks, or upgraded sound.
If you are not at fault, you are also entitled to claim your losses from the at-fault driver's insurer, including the cost of a replacement car. That claim sits alongside the write-off settlement, not inside it. Keep the two separate in your mind and in your correspondence.
Do not accept an offer on the spot. Ask for it in writing, with the valuation basis, and take a day to check it against the market.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Why prestige cars are often undervalued in offers
Insurers value cars using guide books and historical sales data. Those tools work reasonably well for a base-model Corolla, but they struggle with a well-optioned European car. A BMW X7 with the M Sport package, panoramic roof, and upgraded leather is not the same car as a base X7, yet the guide may not reflect the difference.
There are several reasons prestige cars get undervalued:
- Options are not captured. A Porsche with carbon-ceramic brakes or a Mercedes-AMG with a performance exhaust may be valued as a standard model.
- Service history is ignored. A full dealer logbook with recent major service adds real value, especially to a buyer.
- Low kilometres are not rewarded. A 2020 Range Rover Sport with 30,000 km is worth more than one with 90,000 km, but the guide may use an average.
- Colour and condition matter. A rare colour or a car with paint protection film and ceramic coating is worth more to the right buyer.
- Recent work is forgotten. New tyres, brakes, or a recent timing belt service are real money that should be reflected.
If you have receipts for servicing, options, and accessories, send them to the insurer with your response. A well-documented challenge often moves the offer. If the insurer will not budge, you can escalate to the Australian Financial Complaints Authority (AFCA), but that takes time. In the meantime, your replacement car claim continues.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimYour entitlement to a replacement while you decide
When your car is written off, you still need to get to work, drop the kids at school, and attend medical appointments. If you are not at fault, you are entitled to a replacement car that is like-for-like with the car you lost, for a reasonable period while your claim is resolved and you buy a new car. This is known as loss of use, and it is separate from the write-off settlement.
Like-for-like means a similar make, model, and specification. If you drove a Range Rover Sport, a small hatchback is not like-for-like. The replacement should be prestige, automatic, and suitable for your needs. You can read more about what like-for-like means on our like-for-like page.
Credit hire is the mechanism that makes this work. A credit hire company provides the replacement car on credit, and the at-fault driver's insurer pays the hire cost at the end. You do not pay upfront. The rate, the bond, and any fees are shown on the car's page before payment. To understand how the process works, see our how credit hire works guide.
Bookings are fulfilled by Drive Tribe (drivetribe.com.au), and this site is part of that group. If you need a prestige replacement now, you can check availability and book online through accident replacement car Sydney.
Keep the hire going while you negotiate the write-off. The two claims run in parallel, and ending the hire early can weaken your position.
How long you can keep the hire after a write-off
There is no fixed number of days. The test is reasonableness. You can keep the replacement car for as long as it reasonably takes to settle your claim and buy a replacement vehicle. In practice, that is often two to four weeks after the write-off is agreed, but it can be longer if the insurer delays or if you need time to find the right car.
Insurers sometimes argue that hire should stop the moment the write-off offer is made. That is not correct. You are entitled to a replacement while you decide whether to accept the offer, negotiate, and then source a new car. If you accept an offer on a Friday, you cannot reasonably be expected to buy a car by Monday.
What counts as reasonable depends on:
- How quickly the insurer responds to your counter-offer.
- Whether you need to arrange finance.
- Availability of a suitable replacement car in your price range.
- Any delays caused by the insurer's own processes.
If the insurer pressures you to return the hire car, ask for its reasons in writing. Then respond with your timeline and the steps you are taking. Our guide on insurer hire car claim timelines sets out how these arguments usually play out.
If you are unsure how long you can keep the car, ask the credit hire company managing your replacement. They deal with this daily and can advise on the likely period.
Negotiating the settlement without losing the hire claim
The biggest mistake people make is accepting a low write-off offer to keep the hire car, or returning the hire car to speed up the settlement. The two are separate. You can negotiate the settlement hard while keeping the replacement car, provided you are reasonable about the time you take.
Here is a practical approach:
- Put your counter-offer in writing, with evidence. Include comparable sales, service records, and option lists.
- Give the insurer a deadline to respond, usually seven days.
- Keep the hire car. Do not return it as a bargaining chip.
- If the insurer refuses to move, ask for its complaints process and then escalate to AFCA if needed.
- Keep a diary of every call, email, and letter, with dates and names.
Insurers sometimes threaten to stop paying hire if you do not accept the write-off offer. That threat is often bluster, but you should take it seriously. Respond in writing, confirm you are not at fault, and confirm you are entitled to a like-for-like replacement while the claim is resolved. Our page on insurer arguments and rebuttals has the common lines and how to answer them.
If the insurer has already made a low offer, see our guide to low-ball equivalence offers.
If the amounts are significant, or the insurer is being difficult, it may be time to involve a solicitor. Our page on when to get a solicitor explains the signs.
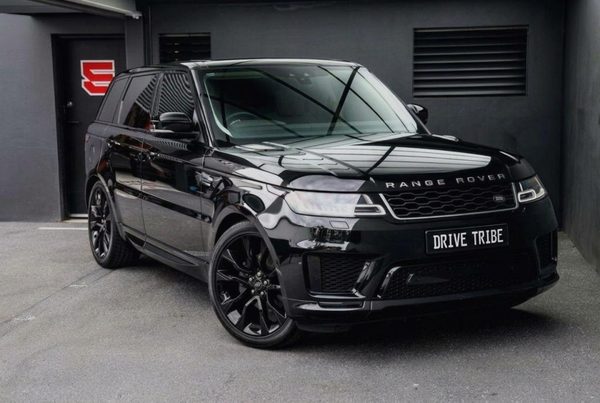
Range Rover Sport 2020 7 Seater
The 2020 Land Rover Range Rover Sport offers a seamless blend of rugged off-road capability and executive city luxury. Featuring a sleek design and a comfortable, high-end cabin,...
Buying your next car: timing and finance
Once the write-off settlement is agreed, you need a new car. The timing matters because your replacement hire will end at some point, and you do not want to be without a car. Start looking as soon as you know the likely settlement figure, even before the money lands.
Finance can be the slow part. If you are financing the next car, get pre-approval early. If you are waiting for an insurance payout to use as a deposit, ask the insurer for a payout timeline in writing. Some insurers release funds within a few days of agreement; others take longer.
Consider these steps:
- Decide on your budget, including any gap between the settlement and the replacement cost.
- Check whether your policy included new-for-old replacement, which may cover a new car of the same model if yours was new or near-new.
- Look at dealer stock and private sales. Prestige cars can be scarce, especially performance models.
- Arrange a pre-purchase inspection for any private sale.
- Keep the replacement hire until you have the new car registered and insured.
If you need a prestige car while you shop, you can book a like-for-like replacement through not at fault accident replacement. The rate, bond, and fees are shown on the car's page before payment.
Here are three prestige SUVs that often suit drivers coming out of a written-off European car.
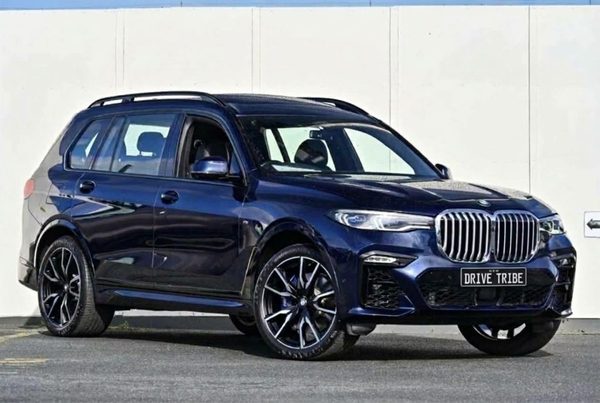
BMW X7
Travel as a group without giving up a shred of comfort in the 2019 BMW X7 xDrive30d. Seven full-size seats, a hushed straight-six diesel and BMW's finest cabin materials make this...
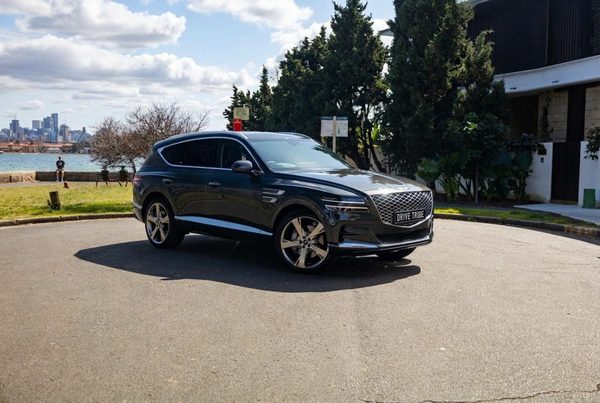
Genesis GV80 3.0D LUX 7 Seat 2023
The Genesis GV80 3.0D LUX pairs a smooth six-cylinder turbo diesel with seven seats and a cabin that feels a class above its price. Strong, effortless torque makes light work of a...
What to do if the offer is clearly too low
If the insurer's offer is well below what your car is worth, do not accept it. You have options. The first is to challenge the valuation with evidence. The second is to escalate within the insurer's internal complaints process. The third is AFCA.
Start by requesting the valuation report. Then gather your own evidence:
- Three to five comparable sales from carsales.com.au or dealer listings, with similar kilometres and options.
- Your full service history and receipts for recent work.
- Photos of the car before the accident, showing condition.
- A written quote from a dealer for a similar car.
Send this to the insurer with a clear counter-offer. Give a deadline. If the insurer rejects it without proper reasons, ask for the complaint to be escalated. AFCA can review the decision, but it can take weeks or months. Your replacement car claim should continue during this time.
If the insurer is arguing that your car was not worth what you say, our guide to low-ball equivalence offers for prestige cars has more detail. If the dispute is about fault, see liability disputes.
Do not sign a release or accept a payment as full and final settlement until you are satisfied. Once you accept, it is very hard to reopen.
The first 24 hours after a write-off decision
When the insurer tells you your car is a write-off, the first day matters. You need to secure the replacement car, start the claim, and protect your position.
Here is what to do:
- Ask the insurer for the write-off decision in writing, including the assessed value and the reasons.
- Contact a credit hire company to arrange a like-for-like replacement. Have your licence, claim number, and accident details ready.
- Do not sign anything from the insurer until you have read it fully.
- Take photos of your car if you still have access, and remove personal belongings.
- Notify your finance company if the car is financed.
- Start gathering comparable sales for your counter-offer.
If you are not at fault, you can also read our first 24 hours guide and our not at fault explained page. For a broader overview of the replacement process, see written off not at fault.
If you need to book a replacement now, you can check availability online. The rate, bond, and fees are shown on the car's page before payment.
Questions people ask
Can I keep the replacement car after a write-off?
How long do I have to accept a write-off offer?
Does a write-off end my loss of use claim?
What if the insurer's offer is lower than my car's value?
Can I buy my written-off car back from the insurer?
How do I arrange a replacement car after a write-off?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe.
Start my claim