Common Insurer Arguments and How to Answer Them
When an insurer argues against your not-at-fault hire car claim, the answer is almost always in the documents you already have: the police report, the repair authority, your own photographs, and the written reasons the insurer has given. This page sets out the eight arguments that come up most often in New South Wales and the documented response to each, so you can reply in writing rather than argue on the phone.
Nothing here is legal advice. It is a practical guide for drivers of prestige and performance cars, fleet managers, repairers and solicitors who need to rebut an insurer hire car denial without guessing.
Key takeaways
- Insurers rarely dispute liability and hire entitlement at the same time; separate the two and answer each on its own terms.
- The correct comparison for rate is a like-for-like vehicle, not the insurer's cheapest preferred supplier.
- A daily log of trips, suburbs and kilometres is the strongest evidence that a replacement car was reasonably necessary.
- Repair duration disputes are won with a chronology showing who controlled each delay, especially parts and assessor approvals.
- Put every rebuttal into one written response with attachments in the order you reference them, and ask for a decision by a stated date.
- You did not need a car at all
- The hire rate is higher than our preferred supplier
- You should have claimed on your own insurance
- We have not accepted liability yet
- The repair should have been quicker
- You kept the car longer than necessary
- The car you hired was better than yours
- Putting the rebuttals together in one response
You did not need a car at all
This is the opening move. The insurer says your car was drivable, or that you have access to another vehicle, or that public transport was adequate. In New South Wales the test is not whether you could physically move, but whether the replacement was reasonably necessary given your circumstances. A 2019 BMW M4 with a cracked front bumper and a failed parking sensor is not a car you can safely leave at a kerb in Double Bay while you wait six weeks for parts.
Answer with specifics. List the days you needed the car: the school run from Mosman to North Sydney, the client meetings at Barangaroo, the 6am site visit at Eastern Creek. If your car was towed to a repairer in Artarmon and you live in Cronulla, say so; the insurer's own assessor chose the repairer. If you had a second car but your partner uses it for work, say that too, with dates.
Keep a simple log. Date, purpose, suburbs, kilometres. It takes two minutes a day and it is the single most useful document when an insurer claims you did not need a vehicle. The same logic applies whether you are in a Tesla Model 3 Performance or a Ford Ranger Wildtrak used for site work.
Tesla Model 3 Performance
For the broader test, see not at fault explained and like for like.
The hire rate is higher than our preferred supplier
Insurers often compare your prestige hire rate to a compact car from their own panel. That comparison fails because the correct measure is the cost of hiring a comparable vehicle, not the cheapest vehicle on the market. A 2021 Audi Q7 Quattro with seven seats, diesel torque and all-wheel drive is not equivalent to a small SUV from a depot at Mascot.
Put the comparison in writing. State the make, model, year and specification of your own car. State the make, model and specification of the replacement. Then state what the insurer's preferred supplier would have provided. If the answer is a different class of vehicle, the rate argument falls away.
You can also point to the market. Prestige hire rates in Sydney move with demand: the weeks around the Australian Open and the spring racing carnival at Randwick are busier than a wet Tuesday in July. Rates reflect availability, delivery to your door in Paddington or Parramatta, and the fact that the vehicle is self-drive with a minimum driver age of 20 on most cars and 25 or 30 on some.
If the insurer still pushes, ask for their written basis. A rate assertion without a comparable quote is not a reason to reduce your claim. More on this in low ball equivalence offers.
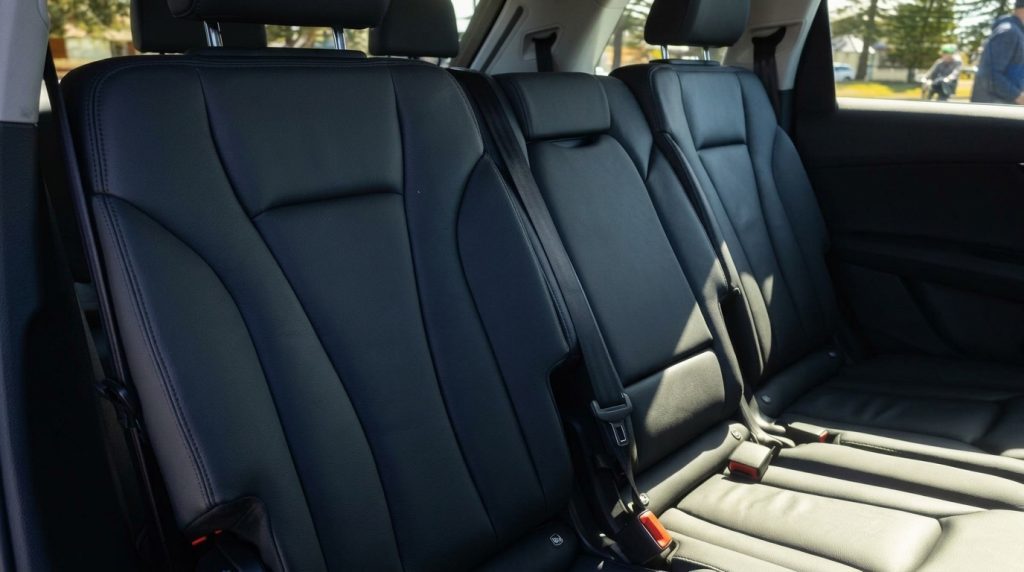
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
You should have claimed on your own insurance
You are not required to use your own policy. If the other driver was at fault, your claim sits against their insurer, and using your own policy can trigger an excess, affect your no-claim bonus and leave you with a hire car entitlement set by your own product disclosure statement rather than by the other party's liability.
The practical answer is to keep the two tracks separate. Notify your own insurer if your policy requires it, but make clear you are claiming against the at-fault party. Do not accept a cash settlement from your own insurer for the hire component without checking what you are giving up.
Credit hire exists for exactly this situation: the hire is provided now, and the cost is recovered from the at-fault insurer later. You can read how the arrangement works at how credit hire works. If you would rather pay and seek reimbursement, that is a choice, and the trade-offs are set out by Drive Tribe at credit hire vs paying yourself.
Where the at-fault driver is uninsured or unidentified, the analysis changes. That is a different conversation, and it is worth taking advice before you commit to a long hire.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimWe have not accepted liability yet
Insurers use this to stall. Liability and hire entitlement are related but not identical, and a delay in accepting fault does not automatically extinguish your right to a replacement vehicle. What it does mean is that the hire provider carries more risk, which is why documentation matters.
Send the insurer everything that supports fault: the police event number, the scene photographs, the other driver's details, witness names, and any dashcam footage. If the other driver was issued with an infringement notice, say so. If the incident happened at the intersection of Military Road and Spit Road at 8.15am, put the time and location in writing.
Then ask for a decision date. A short, polite email that says "please confirm your position on liability by [date]" creates a record. If the insurer continues to sit on it, the next step is usually a formal complaint and then escalation. The process is set out in liability disputes not at fault and insurer complaints and escalation.
Keep hiring if the vehicle is genuinely needed. Stopping the hire because liability is unresolved can leave you without transport for weeks and weaken your position later.
The repair should have been quicker
This argument is about duration. The insurer says the repair took too long, so part of the hire is not recoverable. The answer is to show why the repair took the time it did, and who controlled the timeline.
Prestige repairs in Sydney are frequently delayed by parts. A replacement bumper for a European performance car may come from interstate or overseas, and a repairer in Alexandria or Silverwater may wait weeks for a specific sensor, module or trim piece. That is not your delay. It is the nature of the vehicle.
Build a chronology:
- Date of the accident and date the car was towed.
- Date the repairer received the authority to proceed.
- Dates parts were ordered and dates they arrived.
- Dates the insurer's assessor attended or approved supplementary work.
- Date the car was ready for collection.
If the insurer's own assessor delayed approval, the chronology shows it. If the repairer was waiting on a part, the invoice or order confirmation shows it. For a realistic view of timeframes by model, see how long prestige car repairs take in Sydney.
You kept the car longer than necessary
Insurers sometimes argue that you should have returned the hire car the moment your own car was repaired, or earlier, and that any days beyond that are your responsibility. The usual counter is that you returned the car when it was practical to do so, and that the insurer or repairer controlled when your car was actually ready.
Keep the handover dates. If your car was ready on a Friday afternoon and you collected it on the Saturday morning, that is reasonable. If the repairer told you the car would be ready on Tuesday and it was not ready until the following Monday, the extra days are not yours.
Where the insurer offered a settlement before repairs were complete, or where the car was later written off, the analysis shifts. Read repairs and write offs and insurer write off offers. The key is to avoid gaps: do not keep a hire car after you have your own vehicle back, and do not return it before your own car is genuinely roadworthy.
If you are unsure whether to keep or return the car, ask the provider in writing and keep the reply.
The car you hired was better than yours
This is the like-for-like argument in reverse. The insurer says the replacement was a higher specification than your own car, so you should not recover the full rate. The answer is to compare the two vehicles properly, not by badge alone.
Like-for-like does not mean identical. It means comparable in class, size, transmission, drivetrain and practical capability. A seven-seat diesel SUV replaced by another seven-seat diesel SUV is comparable even if the trim level differs. A dual-cab 4x4 ute replaced by a dual-cab 4x4 ute is comparable even if one has a different tray liner.
Write the comparison down:
| Your car | Replacement | Comparable? |
|---|---|---|
| Seven-seat diesel SUV, AWD | Seven-seat diesel SUV, AWD | Yes |
| Performance sedan, dual motor | Performance sedan, dual motor | Yes |
| Dual-cab 4x4 ute, diesel | Dual-cab 4x4 ute, diesel | Yes |
If the insurer claims the replacement was a category above, ask them to identify the specific feature that makes it so. Vague assertions about "better" are not evidence. See like for like replacement car meaning in NSW.
Putting the rebuttals together in one response
Do not send eight separate emails. Insurers handle volume, and a single clear response is easier to assess and harder to ignore. Structure it so the reader can follow the logic without hunting for attachments.
- Incident summary: date, time, location, police event number.
- Liability position: what you say happened and the evidence that supports it.
- Need for a replacement: your log, your circumstances, why public transport or a borrowed car was not workable.
- Like-for-like comparison: your car versus the replacement, in a short table.
- Rate and duration: the market basis for the rate and the chronology of the repair.
- Request: a decision on liability and the hire component by a stated date.
Attach the documents in the order you reference them. Keep the tone factual. If the insurer responds with a low offer, do not accept it on the phone; ask for it in writing and take advice.
If the dispute is now about the repairer, read insurer preferred repairer rights. If it is about the hire itself, the source material at common reasons an insurer disputes a hire car claim is a useful cross-check. For fleet matters, see business and fleet.
When you are ready to arrange a replacement, bookings are fulfilled by Drive Tribe (drivetribe.com.au), and this site is part of that group. Cars can be booked from a single day, with delivery available across Sydney.
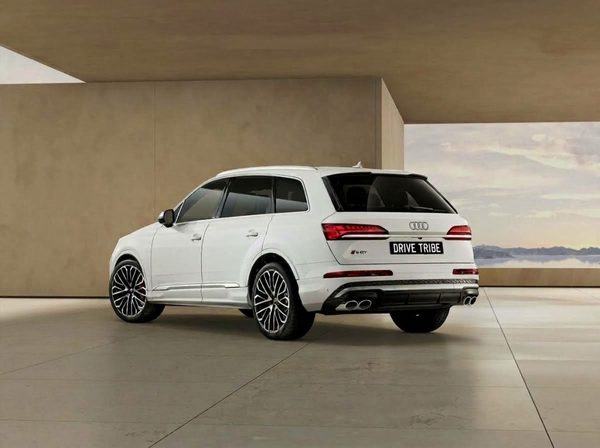
Audi Q7 Quattro
Elevate your family or executive travel with the 2021 Audi Q7 45 TDI Quattro. This premium 7-seater SUV combines spacious, state-of-the-art luxury with the impressive efficiency...
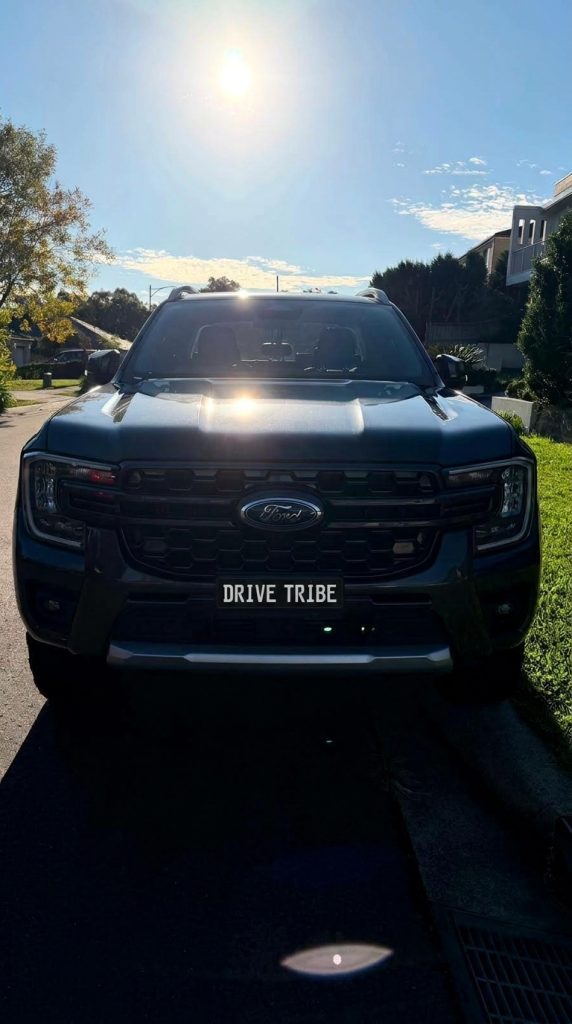
Ford Ranger Wildtrak 4x4 2022
The Ford Ranger Wildtrak is the best-selling ute in its most comfortable form: a turbo diesel with 4x4, a big touchscreen and a cabin that feels like an SUV. Load the tray for the...
Questions people ask
What if the insurer says my hire rate is too high?
Does the insurer have to use my preferred hire company?
How do I prove I needed a car?
Can the insurer insist I use their preferred repairer?
What if the insurer delays accepting liability for weeks?
Should I get a solicitor involved?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe.
Start my claim