Insurer Hire Car Claim After a Crash on a Wet Sydney Road
If you were hit on a wet Sydney road, you can still claim a replacement car from the at-fault driver's insurer even if the insurer argues the rain made the crash your fault. The key is evidence: dashcam, witnesses, weather records and a clear statement of what the other driver did.
This guide explains how insurers handle wet-weather fault disputes, how to gather proof, and how to get a like-for-like prestige replacement car when demand spikes after rain. It covers timelines, escalation to AFCA and when to involve a solicitor.
Key takeaways
- Insurers often dispute fault in wet weather by arguing speed or conditions, but you can counter with dashcam, witnesses and weather reports.
- You are entitled to a like-for-like replacement car even if the insurer disputes fault, and credit hire lets you defer payment.
- After heavy rain, book your replacement car early because demand spikes and prestige vehicles are limited.
- Repairs take longer when many cars are damaged, so keep your hire car until your car is repaired or written off and settled.
- If the insurer delays or denies your claim, escalate to AFCA after lodging an internal complaint.
- Why insurers dispute fault in wet weather crashes
- Gathering evidence: dashcam, witnesses, weather reports
- The 'driving too fast for conditions' argument
- Getting a replacement car when demand spikes after rain
- How long repairs take when many cars are damaged
- When to involve a solicitor for a disputed claim
- Escalating to AFCA if the insurer delays
- Keeping your prestige car's replacement like-for-like
- What to do in the first 24 hours after a wet-weather crash
Why insurers dispute fault in wet weather crashes
Insurers look for any reason to reduce or deny a claim. In rain, they often argue that speed, tyres or following distance contributed to the crash, even when the other driver ran a red light or rear-ended you. The strategy is to create a contributory negligence argument, which can cut your payout and delay your replacement car.
Sydney's wet weather brings specific hotspots: the M4 Motorway at Parramatta, the M5 at Beverly Hills, Victoria Road through Drummoyne, and the Pacific Highway at Chatswood. These roads drain poorly, and standing water causes aquaplaning. Insurers know this and may claim you should have adjusted your driving.
They also rely on police reports that note 'wet road' as a condition. That notation is not an admission of fault. Your job is to separate the weather from the cause. If the other driver failed to give way, changed lanes without indicating, or rear-ended you, the rain is irrelevant to liability.
Under the Civil Liability Act 2002 (NSW), a driver owes a duty of care to other road users. If they breached that duty by driving negligently in the rain, they are liable. Your claim for a replacement car is a loss-of-use claim, and it stands even if the insurer disputes fault initially.
Remember: most insurers will eventually accept liability when faced with clear evidence. The dispute is often a tactic to buy time or pressure you into a low settlement. Stand your ground and document everything.
Gathering evidence: dashcam, witnesses, weather reports
Evidence wins wet-weather claims. Start collecting it immediately, while memories are fresh and footage is available.
- Dashcam: If you have one, download the footage to your phone and cloud storage. Note the time and location. If you don't, ask nearby businesses if they have CCTV. Servos, cafes and car parks along Parramatta Road or Military Road often have cameras.
- Witnesses: Get names and phone numbers. A neutral witness who saw the other driver run a red light is gold. Ask them to write a short statement and sign it.
- Photos: Photograph all vehicles, the road surface, skid marks, traffic lights and street signs. Take wide shots and close-ups. If it is still raining, capture the conditions.
- Weather reports: Download the Bureau of Meteorology observation for the nearest station at the time of the crash. This proves it was raining but does not prove you were speeding.
- Police report: If police attended, get the event number. If not, you can still report the crash online. The report will note the conditions but not fault.
Store everything in one folder. When the insurer asks for your version, provide a concise statement: what you were doing, what the other driver did, and how the crash happened. Avoid speculating about speed or blaming the rain.
If the insurer claims you were speeding, they must prove it. Without a police speed measurement or crash reconstruction, their argument is weak. Your evidence of the other driver's actions is stronger.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
The 'driving too fast for conditions' argument
This is the insurer's favourite wet-weather defence. They will say you were driving too fast for the conditions, even if you were under the limit. In NSW, the speed limit is a maximum, not a target, and drivers must adjust to conditions. But the insurer must show your speed caused the crash.
If you were rear-ended, your speed is irrelevant. The driver behind failed to keep a safe distance. If the other driver turned across your path, your speed did not cause the crash; their failure to give way did. If you aquaplaned and hit them, the argument may have some traction, but only if your tyres were bald or you were driving recklessly.
Counter the argument with facts:
- Your speed relative to the limit and traffic flow.
- Your tyre tread depth and condition (keep receipts for recent replacements).
- Your car's safety features, such as ABS, traction control and all-wheel drive.
- Witness accounts of the other driver's manoeuvre.
- Dashcam footage showing your steady speed and the other car's sudden movement.
Insurers often drop this argument when you provide a clear, consistent account and evidence. If they persist, ask for their evidence in writing. They rarely have any beyond the police report's weather note.
If you need a replacement car while the dispute continues, you can still arrange a credit hire vehicle. The hire is on a deferred basis, and the at-fault insurer is ultimately liable. To see how that works, visit not-at-fault accident replacement.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimGetting a replacement car when demand spikes after rain
After a major rain event, Sydney's smash repairers and hire car fleets are stretched. A storm that hits on a Friday afternoon can leave hundreds of cars damaged by Monday. Prestige and performance cars are especially affected because they need specialised repairers and like-for-like replacements.
Book your replacement car as soon as liability is accepted, or even before if you have a strong case. Credit hire companies can provide a car on a deferred payment basis, meaning you do not pay upfront. The at-fault insurer is billed later.
Availability is tighter for luxury SUVs and performance models. If you drive a Range Rover Sport, Porsche Macan or Audi Q7, you need a provider that holds those cars or can source them quickly. Delivery to your home or workplace in suburbs like Mosman, Bondi or Castle Hill can save you time.
Be flexible on colour and trim. If you need a car for school runs, client meetings and weekend trips, a similar model in a different colour is better than waiting weeks for an exact match. The law requires like-for-like, not identical.
Here are cars that are often available for prestige replacements:
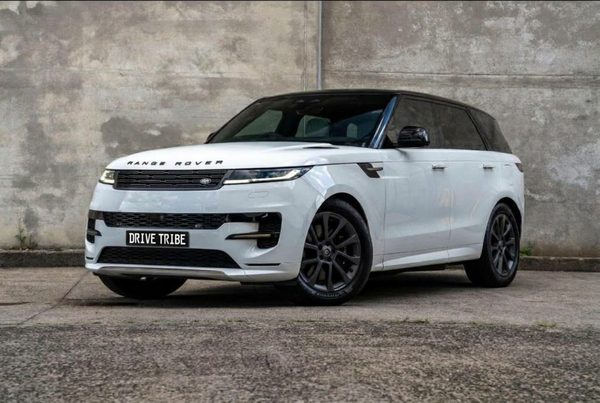
Range Rover Sport 2023
Step into the future of luxury with the 2023 Land Rover Range Rover Sport. Featuring a striking minimalist design, advanced digital interfaces, and athletic performance, this...
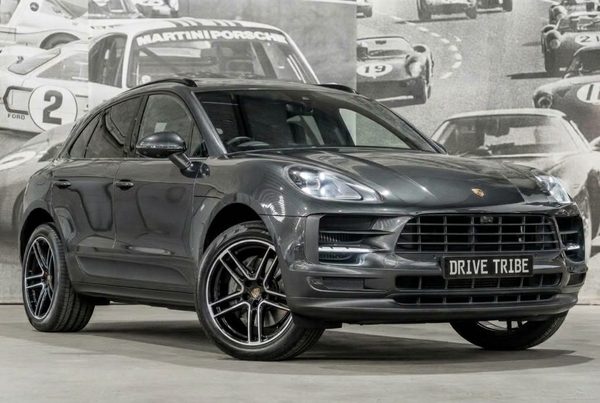
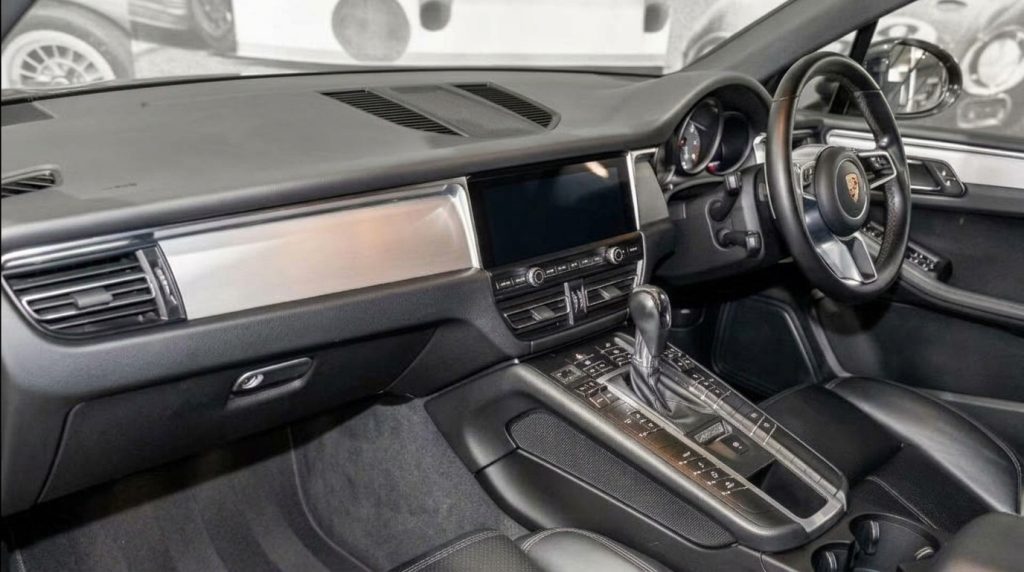
Porsche MACAN
2019 Porsche MACAN...
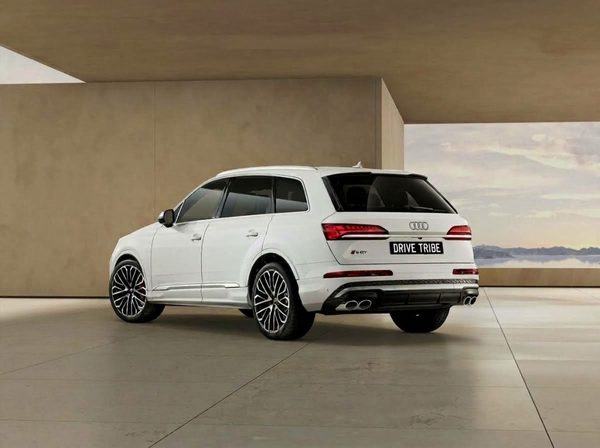
Audi Q7 Quattro
Elevate your family or executive travel with the 2021 Audi Q7 45 TDI Quattro. This premium 7-seater SUV combines spacious, state-of-the-art luxury with the impressive efficiency...
Bookings are fulfilled by Drive Tribe (drivetribe.com.au), and this site is part of that group. You can check availability and have the car delivered to your address.
How long repairs take when many cars are damaged
After widespread rain, repair timelines blow out. A job that normally takes two weeks can take six or more. Reasons include:
- Repairer backlog: shops in Artarmon, Alexandria and Silverwater fill up fast.
- Parts delays: prestige parts often come from overseas, and supply chains slow down after a spike in demand.
- Insurer assessment queues: assessors are overwhelmed, and approvals stall.
- Towing and storage: cars wait days to be moved from holding yards.
Your replacement car should continue until your car is repaired and returned to you, or until you are paid out if it is a write-off. Keep pressure on the repairer and insurer for regular updates. If delays are excessive, you may be entitled to additional loss-of-use compensation.
Document every delay. Note dates of calls, emails and promises. If the insurer keeps pushing back the repair date, that is evidence for a complaint or escalation.
For a detailed timeline, see our guide to how long prestige car repairs take in Sydney. It explains typical waiting periods and how to speed things up.
If your car is written off, the replacement car should continue until the insurer pays you the agreed value. Do not return the hire car early just because the repairer says the car is a write-off; wait for the settlement.
When to involve a solicitor for a disputed claim
Most wet-weather claims resolve without a solicitor. But if the insurer denies liability, alleges contributory negligence, or makes a low offer, a solicitor can help. Consider legal advice if:
- The insurer claims you were partly at fault and reduces your payout.
- They refuse to provide a replacement car despite clear evidence.
- They delay for months without explanation.
- Your car is a write-off and the offer is far below market value.
- You suffered injuries and the claim is complex.
A solicitor can write a letter of demand, negotiate with the insurer, and if necessary, commence proceedings. For credit hire, the hire company may have its own legal team to recover costs, but your personal injury or property damage claim may need separate representation.
Many solicitors offer a free initial consultation for motor accident claims. Ask about their experience with credit hire and prestige vehicles. For more on when to get a solicitor, see when to get a solicitor.
Do not sign anything from the insurer that releases them from liability without legal advice. Once you sign, you cannot reopen the claim.
Escalating to AFCA if the insurer delays
If the insurer unreasonably delays or denies your claim, you can escalate to the Australian Financial Complaints Authority (AFCA). AFCA is free for consumers and can award compensation, including for loss of use.
Before AFCA, you must lodge a formal complaint with the insurer's internal dispute resolution team. Keep a record of the date you complained and the response. If they do not resolve it within 30 days, you can go to AFCA.
AFCA will review the evidence and make a decision. They often find in favour of the claimant when the insurer has been slow or has not properly considered the evidence. For a step-by-step guide, see insurer complaints and escalation.
Escalation can also speed up your replacement car. Once AFCA is involved, insurers often become more cooperative. But do not wait too long; AFCA has time limits, generally six years from the incident, but sooner is better.
If you are unsure, our article on insurer delays and replacement cars explains your rights.
Keeping your prestige car's replacement like-for-like
Like-for-like means a replacement car that is similar in make, model, age, condition and prestige. If you drive a BMW M3, you should get a comparable performance car, not a base Corolla. The law supports this: in Arsalan v Rixon, the NSW Court of Appeal confirmed that a not-at-fault driver can recover the cost of hiring a replacement vehicle, even if they did not actually hire one.
Insurers sometimes offer a 'courtesy car' from their preferred supplier, which may be a small hatchback. You are not obliged to accept it. You can insist on a like-for-like replacement and arrange it through a credit hire company.
To strengthen your position, have your car's details ready: make, model, year, and any special features. If your car is a performance model, note its power and handling. This helps the hire company match you with an appropriate vehicle.
For more on what like-for-like means, see like-for-like and like-for-like replacement car meaning NSW.
If you need a prestige replacement now, check availability at accident replacement car Sydney.
What to do in the first 24 hours after a wet-weather crash
The first day sets the tone for your claim. Do these things in order:
- Safety first: Move to a safe spot, turn on hazard lights, and call 000 if anyone is injured.
- Exchange details: Get the other driver's name, licence, rego, insurer and phone number. Photograph their licence and rego.
- Document the scene: Photos of damage, road position, traffic lights and weather. Note the time and location.
- Witnesses: Collect names and numbers.
- Police: If the other driver fails to stop or is uninsured, call police. For minor crashes, you can report online.
- Insurer: Notify your insurer, but do not accept fault. Give a factual account.
- Replacement car: Contact a credit hire provider to arrange a like-for-like car. Do this early, especially after rain when demand is high.
For a full checklist, see first 24 hours.
If you are not at fault, you can also read not at fault explained and how credit hire works.
Questions people ask
Can the insurer blame me for a wet road crash?
How do I prove the other driver was at fault in the rain?
Will a replacement car be available after a storm?
How long can I keep the replacement car?
What if the insurer offers a low settlement for my written-off prestige car?
Do I need to pay for the replacement car upfront?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe.
Start my claim