Insurer Hire Car Claim After a Crash on the M1 Pacific Motorway
If you are not at fault in a crash on the M1 Pacific Motorway, the at-fault driver's insurer is liable for your reasonable replacement car costs, even if you live on the Central Coast and the crash happened near Mount White or Ourimbah. You do not have to accept a small hatchback from a city depot; you are entitled to a like-for-like vehicle that matches your own car's size, type and prestige.
This page explains which insurer is responsible when the at-fault driver is from interstate, how to get a replacement car delivered to the Central Coast or Hunter, and what to do when a claim stalls. It is general information only, not legal advice. For your specific circumstances, talk to a solicitor.
Key takeaways
- If you are not at fault in an M1 crash, the at-fault driver's insurer is liable for a like-for-like replacement car, even if they are from interstate.
- You can have a replacement car delivered to the Central Coast or Hunter, and you do not have to accept a smaller car than your own.
- You have the right to choose your own repairer, and the insurer must deal with them reasonably.
- Keep a written log of every call and email; it is your best evidence if you need to escalate to AFCA.
- Credit hire can get you back on the road quickly when the insurer delays accepting liability.
- Why the M1 is a black spot for multi-vehicle crashes
- Which insurer is responsible when the at-fault driver is from interstate
- Getting a replacement car delivered to the Central Coast or Hunter
- The insurer's preferred repairer versus your choice
- How long repairs take when parts come from overseas
- Escalating a delayed claim beyond the insurer's internal review
- When a solicitor is worth the cost on a large claim
- Keeping a record of every call and email
- What to do if the at-fault driver is uninsured
- How credit hire works when the insurer won't pay upfront
Why the M1 is a black spot for multi-vehicle crashes
The M1 Pacific Motorway carries a mix of commuters, heavy vehicles and holiday traffic between Sydney and the Central Coast, and that mix produces multi-vehicle crashes at predictable points. The southbound descent into the Hawkesbury River bridge near Mount White is steep and shaded; a sudden slowdown there can catch out a driver who is already tired after a long day. Ourimbah and the Tuggerah interchanges are another pinch point, especially on Friday afternoons when traffic banks up past the service centre.
Multi-vehicle crashes are messy for liability. When three or more cars are involved, insurers often argue about who hit whom first. You may be clearly not at fault but still find your claim delayed while the insurers sort out their shares. That is frustrating when you are stranded at a service station on the Old Pacific Highway with a damaged prestige car and no way home.
In these situations, the key is to gather evidence early. Dashcam footage, photos of the scene and the other drivers' details all help. If the police attend, ask for the event number. That single reference can unlock a claim that would otherwise sit in a queue.
You can read more about establishing fault in our guide to what not at fault means in NSW.
Which insurer is responsible when the at-fault driver is from interstate
The M1 is a national route, and plenty of at-fault drivers are from Queensland, Victoria or beyond. That raises a common question: which state's rules apply? The short answer is that the crash location usually determines the legal framework. If the collision happened in New South Wales, NSW law and the NSW compulsory third party scheme apply, even if the other driver's insurer is based in Brisbane.
That matters because NSW has a well-established line of authority on not-at-fault replacement cars. The decision in Arsalan v Rixon confirmed that a not-at-fault driver can recover the reasonable cost of a like-for-like replacement vehicle, not just a basic courtesy car. An interstate insurer may not volunteer that information, so you may need to point it out politely and in writing.
The at-fault driver's insurer is the one that should pay, regardless of where their policy was issued. If they are uninsured or their policy is void, you may need to claim through the Nominal Defendant or your own insurer, depending on the circumstances. That is when a solicitor's advice is worth having.
For a deeper look at how liability works, see our page on liability disputes when you are not at fault.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Getting a replacement car delivered to the Central Coast or Hunter
You do not have to travel to Sydney to collect a replacement car. If you live in Terrigal, Erina, Newcastle or anywhere along the M1 corridor, a like-for-like vehicle can be delivered to your home, your workplace or the repairer. Delivery is arranged through the booking process, and the car is brought to you by a trusted third-party provider.
When you book, you will see the rate, the bond and any fees on the car's page before payment. The bond equals the excess you choose. Paying by card carries a small surcharge, while bank transfer and cash on the rental do not. You can book from a single day.
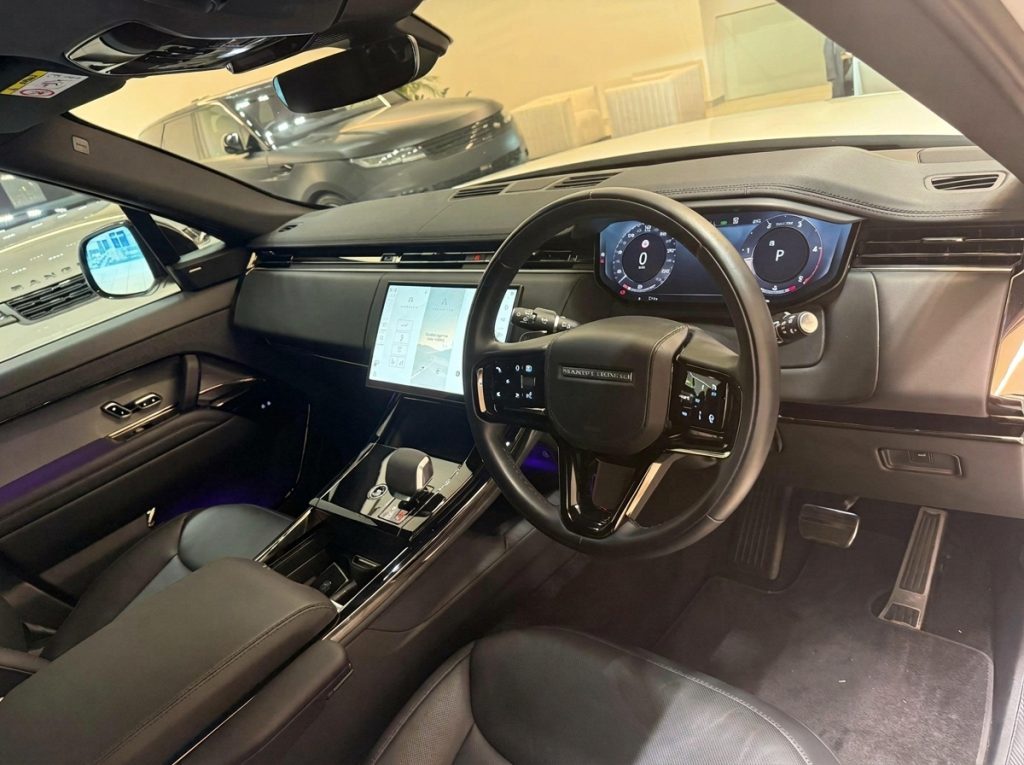
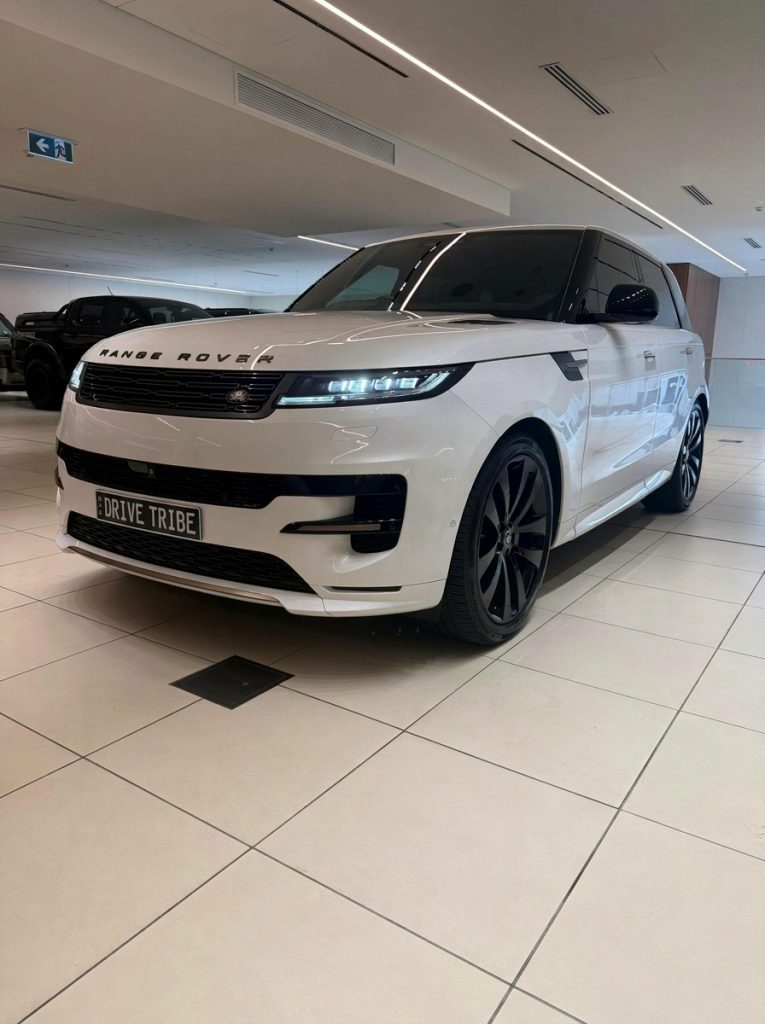
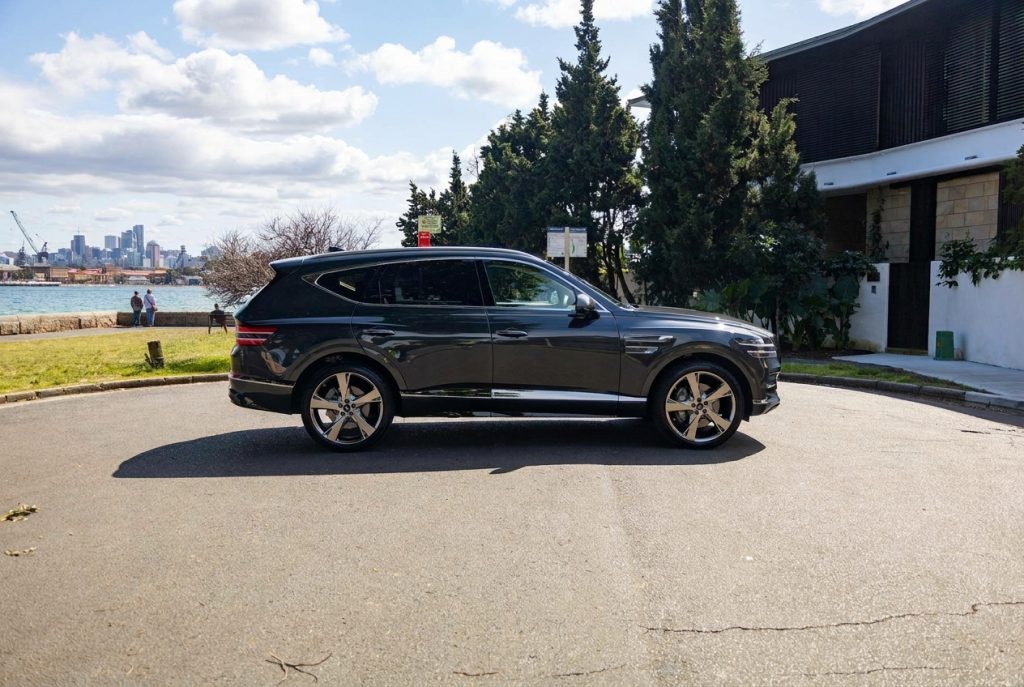
For a prestige car owner, like-for-like means more than four wheels. If your own car is a large luxury SUV, a compact hatchback is not equivalent. A Range Rover Sport or Genesis GV80 is a closer match for space, drivetrain and presence. If you drive a ute, a HiLux Rogue may be the right substitute.
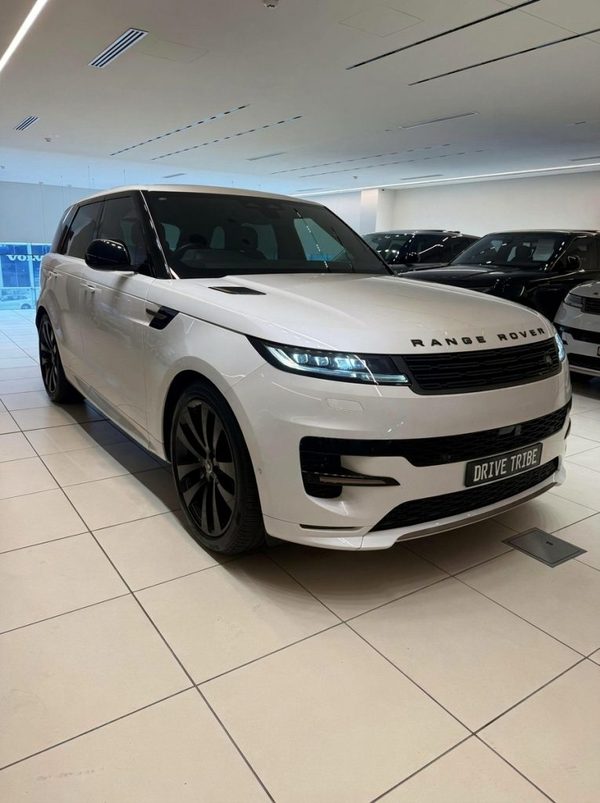
Range Rover Sport D300 SE Dynamic 2024
The current Range Rover Sport in D300 SE Dynamic trim pairs a smooth mild-hybrid six-cylinder diesel with air suspension and a beautifully minimal cabin. It is refined enough for...
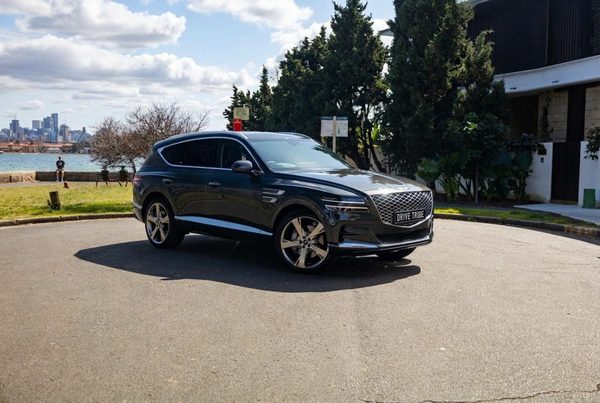
Genesis GV80 3.0D LUX 7 Seat 2023
The Genesis GV80 3.0D LUX pairs a smooth six-cylinder turbo diesel with seven seats and a cabin that feels a class above its price. Strong, effortless torque makes light work of a...
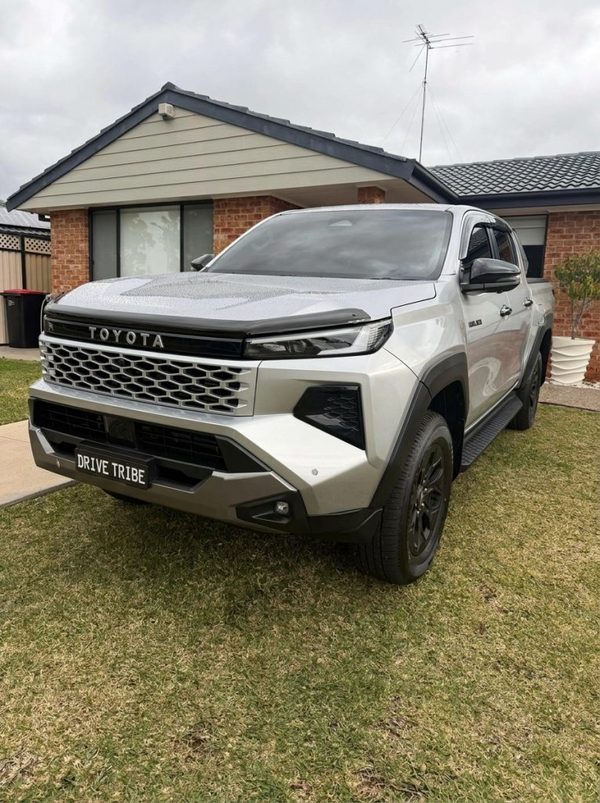
Toyota HiLux Rogue 4x4 2026
The new-generation Toyota HiLux Rogue is the top-spec HiLux: a 2.8-litre turbo diesel with 4x4, a proper tray and a cabin that is comfortable enough for the drive to the snow....
Bookings are fulfilled by Drive Tribe (drivetribe.com.au), the trading name of Australian Business Holdings Pty Ltd, and this site is part of that group. You can check availability and book directly through the car pages.
To understand what like-for-like really means, read our guide to like-for-like replacement cars.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimThe insurer's preferred repairer versus your choice
Insurers often suggest their own repairer network. That can be convenient, but you are not obliged to use their preferred shop. In NSW, you have the right to choose your own repairer, and the insurer must deal with that shop on reasonable terms. The insurer may ask for quotes or an assessment, but it cannot force you into a shop you do not trust.
For prestige and performance cars, the choice of repairer matters more than for a daily driver. Panel alignment, paint matching and calibration of driver-assistance systems require specific equipment and training. A generalist shop may not have the manufacturer-approved jigs or the software to recalibrate radar and cameras after a bumper repair.
If you have a preferred specialist, tell the insurer early. Ask the repairer to provide a detailed estimate and photos. If the insurer pushes back, refer them to your right to choose. If they still refuse, you can escalate the dispute.
Our article on insurer preferred repairer rights explains the process step by step.
How long repairs take when parts come from overseas
Prestige cars often need parts from Europe or Japan, and that can add weeks to a repair. A bumper bracket for a Range Rover Sport may be in stock in Sydney, but a specific headlight or sensor could be on a slow boat from the UK. Your repairer should give you an estimate once the parts are ordered, but delays happen.
During that time, you are entitled to keep a like-for-like replacement car, provided you are not at fault and the other insurer has accepted liability. The length of the hire should match the reasonable repair time. If the repairer says eight weeks, the insurer should not cut off the hire at four.
Keep a written record of the repairer's estimated completion date and any revised dates. If the insurer questions the duration, you can show that the delay is genuine. For more on how long repairs can take, see our guide to how long prestige car repairs take in Sydney.
If the insurer tries to end the hire early, our page on insurer delays and replacement cars has practical steps.
Escalating a delayed claim beyond the insurer's internal review
When a claim stalls, the first step is a written complaint to the insurer's internal dispute resolution team. Put the claim number in the subject line, list the dates of every call and email, and state clearly what you want: acceptance of liability, approval of the hire car, or payment of the repair. Give them a reasonable deadline, such as ten business days.
If that does not resolve it, you can escalate to the Australian Financial Complaints Authority (AFCA). AFCA is free for consumers and can make binding decisions on insurers. Before you lodge, gather your evidence: the police event number, photos, repairer quotes, and a log of your communications.
AFCA can also consider whether the insurer's conduct has been fair. If they have delayed unreasonably, AFCA may award compensation for inconvenience or financial loss. That can include the cost of a replacement car you had to pay for yourself.
For a detailed walkthrough, see our article on insurer complaints and escalation.
When a solicitor is worth the cost on a large claim
Not every claim needs a solicitor. If liability is accepted, the repair is straightforward and the hire car is approved, you can manage it yourself. But some situations justify legal help. If the at-fault driver is uninsured, if the insurer alleges you contributed to the crash, or if your prestige car is a write-off and the offer seems low, a solicitor can make a difference.
Legal costs can be recovered in some cases, but not always. A solicitor will give you advice on your specific circumstances. As a general rule, the larger the claim and the more complex the liability, the more likely it is that legal advice pays for itself.
If you are unsure, start with a free initial consultation. Many firms offer one. Bring your documents: the police report, photos, repairer quotes, and any correspondence with the insurer.
Our guide on when to get a solicitor can help you decide.
Keeping a record of every call and email
Insurers handle thousands of claims, and details can get lost. Your best protection is a simple log. For every call, note the date, time, the name of the person you spoke to, and what was agreed. Follow up with an email summarising the conversation. If they do not reply, you have a record that you tried.
Keep all emails in a dedicated folder. If you use a phone, screenshot the call log. If you send documents by post, keep a copy and a receipt. This may seem tedious, but it is invaluable if you need to escalate to AFCA or a solicitor.
A written timeline also helps your replacement car provider. If the insurer disputes the hire period, you can show exactly when you notified them and what they said. That evidence can speed up resolution.
For more on the first steps after a crash, read our guide to the first 24 hours after a not-at-fault accident.
What to do if the at-fault driver is uninsured
If the at-fault driver has no insurance, you may still be able to claim through the Nominal Defendant, a NSW scheme for crashes involving uninsured or unidentified vehicles. The process is more involved, and you will need to show that you have made reasonable efforts to identify the driver. Time limits apply, so act quickly.
In some cases, your own insurer may cover the repair and replacement car under your policy, but that can affect your no-claim bonus. Check your policy wording. If you are not at fault, your insurer may still pursue the at-fault driver to recover costs.
A solicitor can help you navigate the Nominal Defendant scheme. It is not a quick process, but it exists to protect people in your situation.
For more, see our page on insurer disputes and hire car claims.
How credit hire works when the insurer won't pay upfront
Credit hire is an arrangement where a replacement car is provided to you on credit, and the cost is recovered from the at-fault insurer later. You do not pay upfront. The provider takes on the risk of recovering the cost, which is why they assess your claim carefully before approving a vehicle.
Credit hire is common in not-at-fault claims, especially when the insurer is slow to accept liability. It allows you to get back on the road quickly without waiting for the insurer's approval. The agreement will set out your obligations, including cooperating with the recovery process.
If the insurer disputes the hire rate or duration, the provider may pursue the difference. That is why it is important to choose a reputable provider who understands NSW law and the Arsalan v Rixon principles.
To learn more, read our guide to how credit hire works.
Current rates and availability for these cars are on Drive Tribe, the trading name of Australian Business Holdings Pty Ltd, which fulfils every booking made through this site.
Questions people ask
Can I choose my own repairer after an M1 crash?
Will the insurer pay for a hire car if I live on the Central Coast?
What if the at-fault driver is uninsured?
How long can I keep a replacement car after an M1 crash?
Do I have to accept the insurer's first offer for a write-off?
What should I do in the first 24 hours after a crash on the M1?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe, the trading name of Australian Business Holdings Pty Ltd.
Start my claim