Replacement Car When Your Car Is a Write Off
If your car is written off and you were not at fault, you can keep a replacement car for as long as it reasonably takes to receive your payout and find a replacement, provided the hire is managed properly and the other side has accepted liability. The insurer of the at-fault driver usually covers the reasonable cost of that hire, but only if you can show the car is needed and the rate is fair.
This page explains what a write-off means in New South Wales, how statutory and economic write-offs differ, why the first payout offer often falls short, and how to keep a prestige replacement car on the road while you shop. It is written for drivers of cars worth replacing properly, fleet managers, repairers and solicitors.
Key takeaways
- If you are not at fault, you can keep a replacement car while you wait for the payout and shop for a new car, as long as the hire is reasonable.
- A statutory write-off can never be re-registered; an economic write-off is repairable but not worth repairing to the insurer.
- The first payout offer is often below replacement cost, so gather comparable ads and a specialist valuation before accepting.
- The at-fault insurer usually covers the reasonable cost of a like-for-like replacement, but you must show genuine need and a fair rate.
- If the insurer tries to end the hire early, respond in writing with evidence and consider a solicitor before the deadline.
- What a write-off actually means in New South Wales
- Statutory versus economic write-offs and who decides
- Why the payout offer often lands well below replacement cost
- How long you can keep a replacement car while you shop
- Evidence to gather before you accept any settlement
- Buying your next car while the claim is still open
- If the insurer wants the replacement car back early
- Getting a solicitor involved before you sign anything
What a write-off actually means in New South Wales
In NSW, a write-off is a car that an insurer decides is not worth repairing, or that is so badly damaged it must be removed from the road. The decision is not about whether you love the car. It is a financial and safety judgement made under the Motor Accidents Injuries Act 2017 and the Road Transport Act 2013, and it is recorded on the written-off vehicle register.
There are two paths. A statutory write-off is structurally unsafe or stolen and recovered in a way that makes it unregisterable. It can never go back on the road. An economic write-off is repairable but the repair cost is too high relative to the car's market value, so the insurer pays you out instead. Most prestige cars that are hit hard end up here because parts, aluminium panels and specialist labour add up fast.
If your car is a write-off, the insurer will usually take possession of it, cancel the registration and pay you the agreed value or market value, less any excess if you are at fault. If you are not at fault, you should not be out of pocket for the car itself or for a replacement while the claim is sorted.
Read our full guide to repairs and write-offs for the steps that follow the assessment.
Statutory versus economic write-offs and who decides
The insurer's assessor decides whether your car is a statutory or economic write-off. You do not get a vote, but you can challenge the valuation and you can ask for the assessment report. In Sydney, assessments often happen at a holding yard in places like Smithfield, Blacktown or Banksmeadow, and the car can sit there for days before you hear anything.
Here is the practical difference:
- Statutory write-off: cannot be re-registered. The VIN is flagged. The insurer pays you out and keeps the wreck.
- Economic write-off: repairable, but not economic to repair. You can sometimes buy the salvage back and repair it, but it will carry a write-off flag and be harder to insure and sell.
For a prestige car, the assessor's repair estimate is often based on new genuine parts and a high labour rate. That is why a car with seemingly moderate damage, say a rear quarter panel and suspension on a Range Rover, can be written off when a Corolla would be repaired.
If you disagree with the decision, you can get your own assessment. A specialist prestige repairer in Alexandria or Artarmon can provide a second opinion, and that report can be used in negotiations. Do not authorise repairs yourself before the claim is settled unless you are prepared to fund them.
If the other driver's insurer is involved, they may also want their own assessor to look at the car. That is normal, but it adds time.
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
Why the payout offer often lands well below replacement cost
The first offer is usually based on a database of recent sales, adjusted for kilometres and condition. It rarely reflects what it will actually cost you to walk onto a forecourt in Sydney and buy the same car, same year, same options, same colour, with the same service history, this week.
Common gaps:
- Options and trim: a base model price is used when yours has the performance pack, panoramic roof or upgraded audio.
- Kilometres: a low-kilometre car is worth more, but the database may average it out.
- Service history: a full logbook from a prestige specialist adds value that a generic valuation misses.
- Registration and transfer costs: the payout may not cover the cost of getting a new car on the road.
- Finance and negative equity: if you owe more than the car is worth, the gap does not disappear.
You are allowed to reject the first offer and provide evidence. Advertisements for comparable cars currently for sale in NSW, recent sales receipts, and a written valuation from a dealer or independent valuer all help. Do not accept a figure just because it arrived quickly.
If you need a replacement car while you negotiate, that is exactly what not-at-fault hire is for. The at-fault insurer is expected to cover a reasonable replacement, and the rate, bond and fees are shown on the car's page before payment. Bookings are fulfilled by Drive Tribe (drivetribe.com.au), and this site is part of that group. You can see the current prestige fleet and check availability at https://drivetribe.com.au/accident-replacement-car-sydney/.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimHow long you can keep a replacement car while you shop
There is no fixed number of days in the legislation. The test is reasonableness. If you are not at fault, you are entitled to be put back in the position you were in before the crash, which includes having a comparable car to drive while your claim is resolved and while you find a replacement.
In practice, a not-at-fault replacement car can run from the date of the accident until a reasonable period after the payout is received. For a prestige car, that might be several weeks. The other insurer will often push back after two or three weeks, especially if you have already received an offer.
What keeps the hire defensible:
- Liability accepted. The other driver's insurer has confirmed their insured was at fault.
- Like-for-like. The replacement is comparable to your car, not a base model. See like-for-like.
- Genuine need. You use the car for work, school runs, client meetings or similar.
- Reasonable rate. The daily rate is in line with the market for that type of car.
- Active search. You are genuinely looking for a replacement, not delaying.
If your car is a write-off, the hire period usually ends when you receive the payout plus a short window to buy a new car. If you are still waiting for the payout, the hire should continue. Keep a simple log of the days and what you were doing.
For a deeper look at timelines, see how long prestige car repairs take in Sydney and insurer delays and replacement cars.
Evidence to gather before you accept any settlement
Before you sign a release or accept a payout, build a file. Insurers respond to documents, not assertions. In NSW, the most useful evidence is:
- Photos of your car before the accident. Clean, all angles, showing condition and options.
- Service records. Logbook stamps, invoices from prestige specialists, and any recent major work.
- Comparable advertisements. Screenshot current listings for the same model, year and options in Sydney, with the date and price.
- Your own valuation. A written figure from a dealer or independent valuer who knows the model.
- Accident details. Police report number, dashcam footage, witness names, and the other driver's details.
- Hire records. The replacement car agreement, dates, and why you needed it.
Keep everything in one folder, digital or paper. If you are claiming for a prestige car, a valuation from a marque specialist carries more weight than a generic online estimate.
If you are unsure what to collect at the scene, our evidence checklist covers it. If the accident has just happened, start with the first 24 hours.
Buying your next car while the claim is still open
You do not have to wait for the payout to start looking. In fact, starting early strengthens your position because you can show the insurer you are mitigating your loss. The risk is committing to a purchase before you know the final payout figure.
A practical approach:
- Set a realistic budget based on the payout you expect, not the first offer.
- Shortlist three cars that match your old car's spec, kilometres and condition.
- Get a pre-purchase inspection on any used prestige car. In Sydney, use a specialist who knows the model, not a general mechanic.
- Do not sell your old car's accessories or parts until the claim is settled.
- Keep the replacement car until you have the new one registered and insured.
If you need a car while you shop, a prestige replacement keeps you mobile and keeps the pressure on the insurer. Options include a like-for-like replacement by car type. For a large SUV, the Range Rover Vogue is a common match for a written-off luxury 4WD.
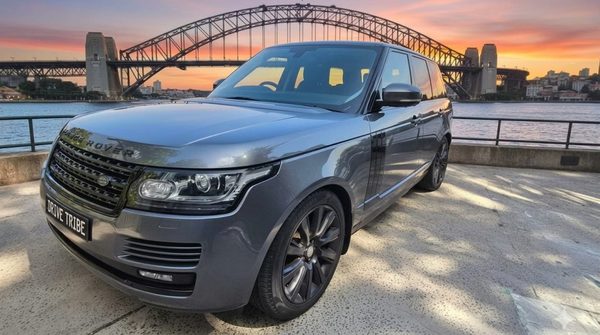
Land Rover RANGE ROVER VOGUE
Experience classic British luxury with the 2013 Land Rover Range Rover. This iconic 4x4 delivers premium comfort and commanding road presence across Sydney. Whether navigating...
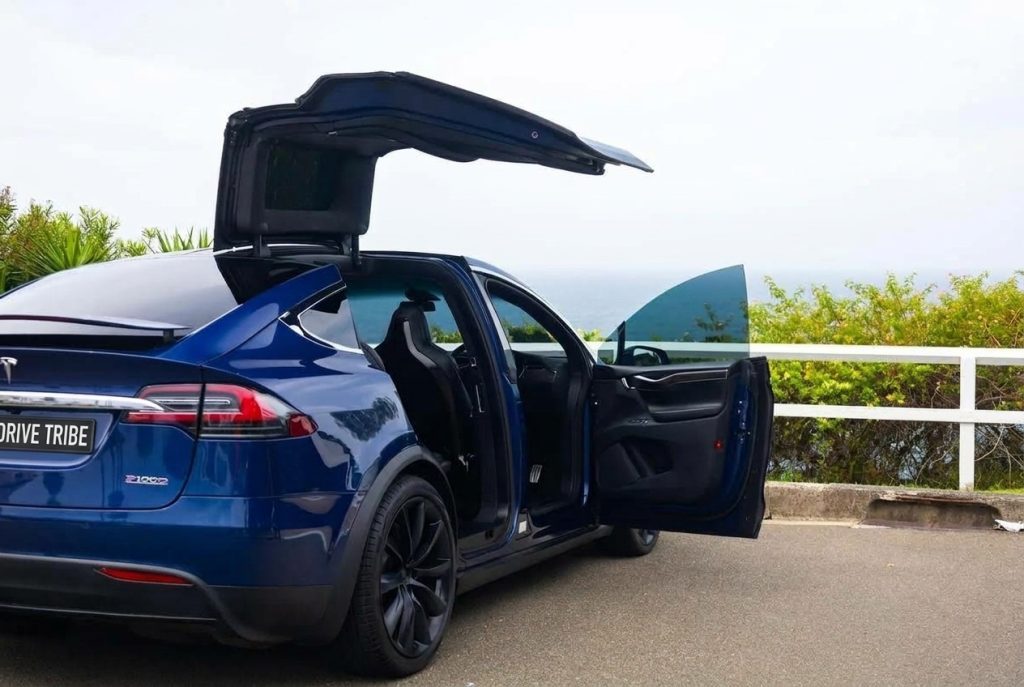
If your written-off car was electric, a Tesla Model X P100D or Porsche Taycan Turbo may be the closest match in performance and space.
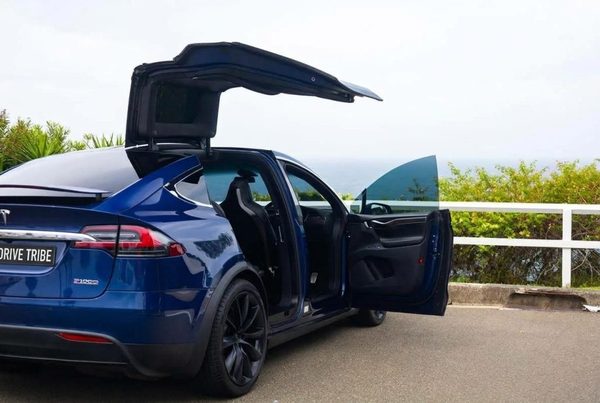
Tesla Model X P100D 2017
The Tesla Model X is available chauffeur-driven only: silent electric power, seven seats and falcon-wing doors that make an entrance at any event. Ideal for corporate transfers,...
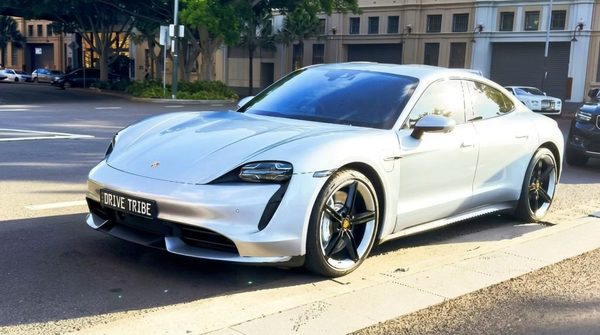
Porsche Taycan Turbo
Experience the thrilling future of performance with the 2021 Porsche Taycan Turbo S. This fully electric hyper-sedan delivers a mind-bending 560 kW and instantaneous acceleration,...
If you drove a dual-cab or American pickup, the Silverado Trail Boss is a comparable lifestyle ute. Note the minimum driver age is 25 on that car.
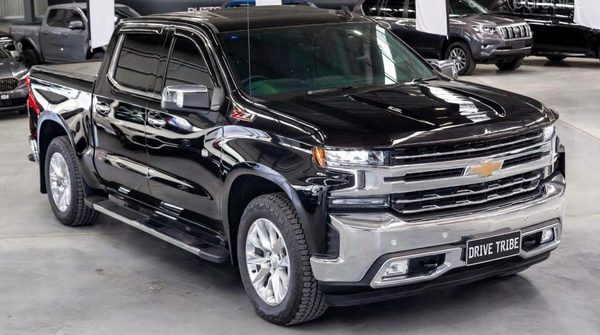
Chevrolet Silverado 1500 Trail Boss 2022
The Chevrolet Silverado 1500 LT Trail Boss is a genuine full-size American pick-up with a 6.2-litre V8, factory lift and off-road hardware. Huge presence, a big comfortable cabin...
If the insurer wants the replacement car back early
It happens. The at-fault insurer sends a letter saying they will only pay for hire up to a certain date, often a date that suits them rather than you. You do not have to hand the car back immediately, but you do need to respond with reasons.
What to do:
- Ask for the decision in writing and the basis for it.
- Provide evidence of continued need. A letter from your employer, a diary of appointments, or proof that you are still car hunting.
- Show the payout has not been received. If the insurer has not paid you, the need for a replacement continues.
- Check the hire agreement. Know your obligations and the notice period.
- Escalate. If the insurer refuses to budge, a letter from a solicitor often resolves it quickly.
Do not ignore the letter. If you keep the car without responding, the insurer may refuse to pay the later portion of the hire, and you could be personally liable. If you are unsure, get advice before the deadline.
Our page on dealing with insurers has more scripts and steps. If you are a repairer or solicitor, see partners and referrals.
Getting a solicitor involved before you sign anything
You can handle a straightforward not-at-fault write-off yourself. But if the insurer is delaying, disputing liability, offering a low figure, or threatening to stop the hire car, a solicitor who works in motor vehicle claims is worth the call. They can write to the insurer, negotiate the payout, and protect you from signing away your rights.
When to get help:
- The other driver's insurer has not accepted liability within a week or two.
- The payout offer is clearly below replacement cost.
- You are being pressured to accept a quick settlement.
- The insurer says they will stop paying for the replacement car.
- You have finance owing on the written-off car.
- You were injured, even mildly.
Most firms will give a free initial chat. Bring your claim number, the assessment report, the payout offer, and your evidence folder. A solicitor can also help you recover the cost of the replacement car if the insurer refuses to pay it.
This is general information, not legal advice. Talk to a solicitor about your circumstances.
If you need a replacement car while the claim is open, check availability with the fleet at https://drivetribe.com.au/not-at-fault-accident-replacement/ or read the source guide at https://drivetribe.com.au/written-off-not-at-fault/.
Questions people ask
Can I keep a replacement car after my car is written off?
Who pays for the hire while I wait for the payout?
Do I have to accept the first settlement offer?
What is the difference between a statutory and economic write-off?
How long does a write-off payout take in NSW?
Can I buy my written-off car back from the insurer?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe.
Start my claim