The Other Driver Is Uninsured: What Happens Now?
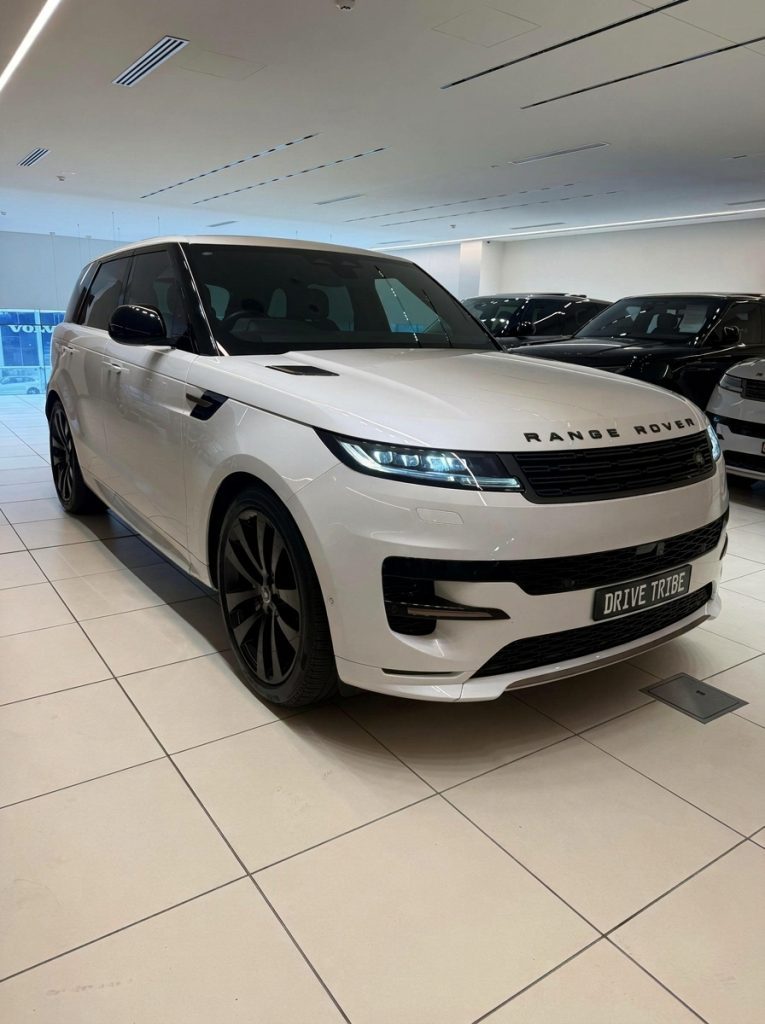
If the other driver is uninsured, you are not automatically left paying for your own replacement car. In New South Wales, the at-fault driver remains personally liable for your losses, and a credit hire arrangement can still put you in a like-for-like vehicle while the claim is sorted out.
What changes is who the recovery is pursued against and how long it takes. Instead of dealing with an insurer, you or your solicitor may need to chase the driver directly, which means gathering evidence and issuing demands. This article explains the process step by step.
Key takeaways
- An uninsured at-fault driver is personally liable for your repair costs and reasonable loss of use, so you can still claim.
- Credit hire can provide a like-for-like replacement car even when the at-fault driver has no insurer, provided the claim is viable.
- Never accept cash or sign anything at the scene, and always exchange full details and gather evidence.
- Recovery from an uninsured driver may require a letter of demand and court proceedings, which a solicitor can handle.
- If negotiations stall, stop engaging directly and let a credit hire company or solicitor take over.
- What uninsured actually means for your claim
- The at-fault driver's personal liability
- How a credit hire agreement works when there is no insurer
- Recovery, demands and the role of a solicitor
- What you should never agree to at the scene
- Getting a replacement car while it is sorted out
- Repair costs and who chases them
- When to stop negotiating yourself
What uninsured actually means for your claim
Uninsured means the at-fault driver has no third-party property damage cover. In NSW, that is a breach of the compulsory third-party insurance scheme, but it does not erase their liability. Your claim is still valid; it just shifts from an insurer to the driver personally.
You have two broad paths. You can claim on your own comprehensive insurance if you have it, pay your excess, and let your insurer recover from the uninsured driver. Or you can pursue the at-fault driver directly, often through a credit hire company that arranges the replacement car and the recovery. The right choice depends on your policy, your tolerance for delays, and whether you want to protect a no-claim bonus.
If you are not at fault, your own insurer should not treat the claim as an at-fault one, but you will likely need to pay your excess upfront and claim it back. That can take months. For prestige and performance cars, the bigger issue is often the hire car: most insurers will only fund a basic replacement, not a like-for-like one. That is where a specialist credit hire provider comes in.
For a full explanation of fault in NSW, see what not at fault means in NSW.
The at-fault driver's personal liability
An uninsured at-fault driver is personally liable for the damage they cause, including your repair costs and your reasonable loss of use. That liability does not disappear because they have no insurance. It simply means you may need to enforce it through a letter of demand, a statement of claim, or a debt recovery process.
In practice, recovery can be slow. The driver may not have assets, may dispute fault, or may simply ignore correspondence. That is why many not-at-fault drivers use a credit hire company: the company takes on the recovery risk and provides the replacement car upfront. You sign an agreement, but you are not out of pocket while the claim is pursued.
If the uninsured driver is identified and has assets, a solicitor can issue a demand and, if necessary, commence proceedings in the Local Court or District Court. The amount you can recover includes the reasonable cost of a replacement vehicle of similar type and quality, which is where like-for-like comes in.
It is important to document everything: the other driver's name, address, licence number, phone number, and vehicle details. Take photos of the scene, the damage, and any skid marks or debris. If the driver refuses to provide details, call the police.
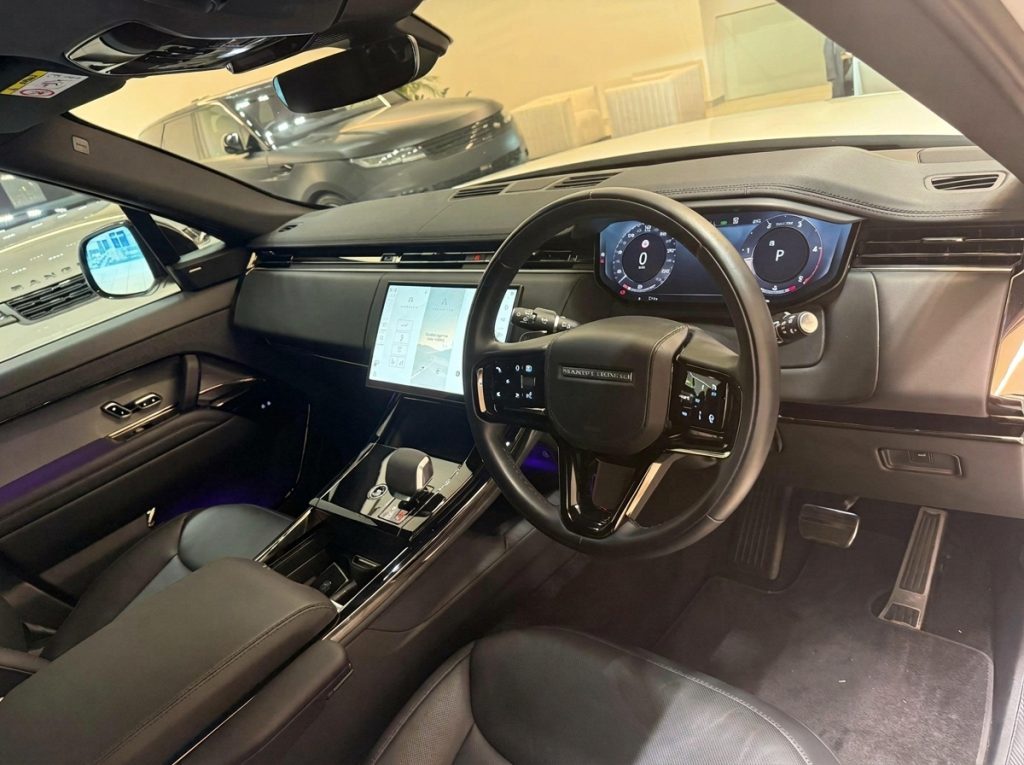
Age limits are set per car. Drivers under 25 can hire most cars with Young Driver Cover; the exact terms are shown before you pay.
How a credit hire agreement works when there is no insurer
A credit hire agreement is a contract where the hire company provides you with a replacement vehicle on credit, and you agree to pay the hire charges from the proceeds of your claim. If the claim succeeds, the at-fault driver or their insurer pays. If it fails, you may be liable, which is why reputable providers assess the claim carefully before accepting it.
When the at-fault driver is uninsured, the credit hire company will typically ask for evidence of fault, such as a police report, witness statements, and photos. They will also check that you have a reasonable prospect of recovering from the driver. If the driver is unidentified or has no assets, the company may decline the hire because recovery is unlikely.
The agreement usually covers the daily rate, the duration of the hire, and the conditions. You should read it carefully. The rate and any fees are shown on the car's page before payment. The bond equals the excess you choose. Paying by card carries a small surcharge; bank transfer and cash on the rental do not.
For a detailed explanation, see how credit hire works and credit hire vs paying yourself.
Not at fault? Start your claim
A like-for-like replacement car while yours is repaired. No cost to you when the other driver is at fault.
Start my claimRecovery, demands and the role of a solicitor
Recovery from an uninsured driver usually starts with a letter of demand. This is a formal letter setting out the amount owed, the basis for the claim, and a deadline for payment. It is often enough to prompt payment or a negotiation, but if the driver ignores it, the next step is a statement of claim in court.
A solicitor can help you prepare the demand and, if necessary, file proceedings. They can also advise on the strength of your case and whether the driver has the means to pay. For claims under a certain threshold, the Local Court has a simplified process. For larger amounts, the District Court may be appropriate.
If you have comprehensive insurance, your insurer may handle recovery on your behalf after you pay your excess. However, they will only recover what they paid out, not your excess or your hire car costs unless you have taken separate steps. That is why some drivers pursue the at-fault driver directly for the excess and hire car costs, even after claiming on their own policy.
Timelines vary. A straightforward demand might be resolved in weeks; court proceedings can take months. A solicitor can give you a realistic estimate based on the driver's response.
What you should never agree to at the scene
At the scene, emotions run high and the other driver may ask you to keep it off the books. Never agree to that. You are entitled to have your car repaired and to a replacement vehicle, and an informal arrangement can jeopardise your claim.
Do not accept cash on the spot. You have no way of knowing the full extent of the damage, and a cash payment may be far less than the repair cost. Do not sign any document the other driver produces, and do not admit fault, even if you think you might be partly to blame. Fault is a legal determination, not a roadside negotiation.
Exchange details: name, address, licence number, phone number, and insurer (if any). If the driver is uninsured, note that. Take photos and videos of the position of the cars, the damage, and the surroundings. Get contact details for any witnesses. If the driver leaves without providing details, call the police.
For a step-by-step guide, see the first 24 hours after a not-at-fault accident.
Getting a replacement car while it is sorted out
You can still get a replacement car if the at-fault driver is uninsured, provided the claim is viable. A credit hire company will assess the evidence and, if they accept the claim, provide a like-for-like vehicle. That means a prestige or performance car of similar type and quality, not a basic hatchback.
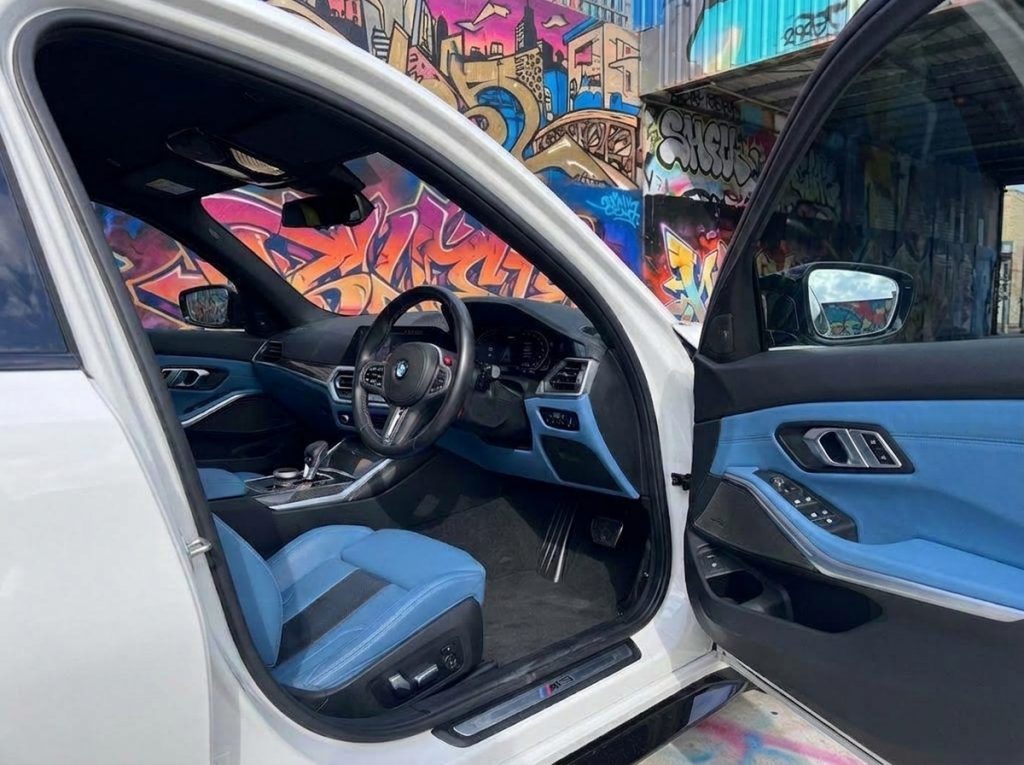
In Sydney, you can collect from a base or have the car delivered. For example, if you drive a Range Rover, a suitable replacement might be a Range Rover Sport D300 SE Dynamic, available from Merrylands with a minimum driver age of 30. If you drive a BMW M car, a BMW M3 Competition G80 from Parramatta (minimum age 25) could be the equivalent. For a seven-seat luxury SUV, a Mercedes-Benz GLS from Mascot (minimum age 20) may fit.
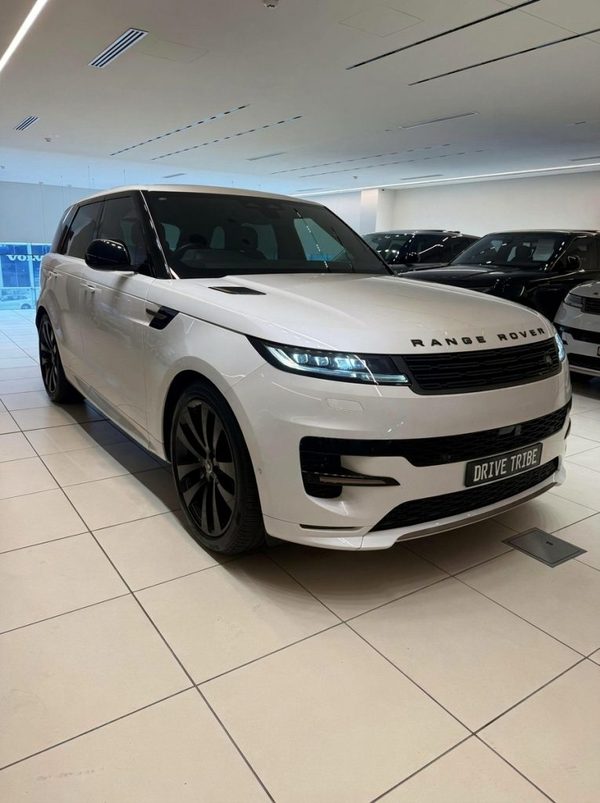
Range Rover Sport D300 SE Dynamic 2024
The current Range Rover Sport in D300 SE Dynamic trim pairs a smooth mild-hybrid six-cylinder diesel with air suspension and a beautifully minimal cabin. It is refined enough for...
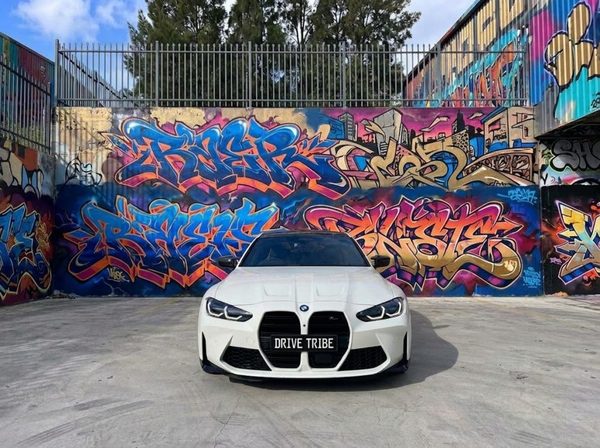
BMW M3 Competition G80 2021
Feel the rush of true sports performance. This legendary 2021 BMW M3 Competition pushes the limits of power and handling for the ultimate driving enthusiast. Cruise through Sydney...
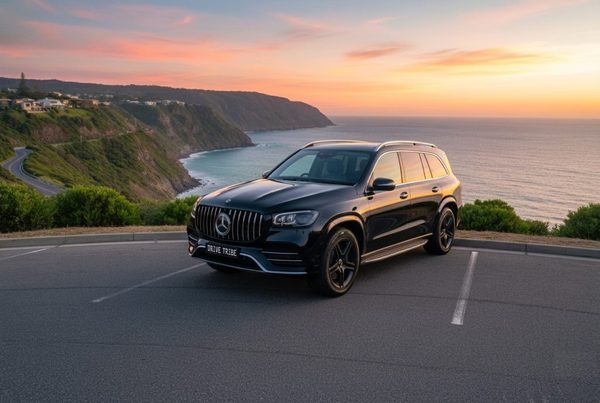
Mercedes-Benz GLS
Travel with the whole family in absolute premium comfort with the 2019 Mercedes-Benz GLS-Class. Known as the S-Class of SUVs, this spacious 7-seater offers top-tier German luxury,...
Bookings are fulfilled by Drive Tribe (drivetribe.com.au), the trading name of Australian Business Holdings Pty Ltd, and this site is part of that group. The rate, bond, and any fees are shown on the car's page before payment.
To understand how equivalence is assessed, see how equivalence is assessed for prestige cars.
Repair costs and who chases them
If the at-fault driver is uninsured, you can either claim on your own insurance or pursue the driver directly for repair costs. If you claim on your own insurance, you will pay your excess and your insurer will seek recovery from the driver. If you pursue directly, you will need to obtain quotes, arrange the repair, and then demand payment.
For prestige cars, repairs can be expensive and require specialised parts and labour. Your insurer may prefer a repairer from their network, but you have the right to choose a repairer, provided the cost is reasonable. If you are pursuing the driver directly, get at least two quotes from reputable prestige repairers.
Keep all receipts and correspondence. If the driver refuses to pay, you can take the matter to court. The amount you can claim includes the reasonable cost of repairs and the reasonable cost of a replacement car while yours is off the road. For more on write-offs, see repairs and write-offs.
When to stop negotiating yourself
Negotiating with an uninsured driver can be time-consuming and stressful. If the driver is unresponsive, disputes fault, or makes unrealistic offers, it is time to involve a solicitor or a credit hire company. They can take over the correspondence and pursue recovery on your behalf.
Signs it is time to stop: the driver stops returning calls; they deny liability despite clear evidence; they offer a small amount to settle; or they ask you to sign a release. Once you sign a release, you may lose your right to claim further costs.
A solicitor can also advise on whether to accept a settlement or proceed to court. For more on disputes, see insurer disputes hire car claim and common reasons an insurer disputes a hire car claim.
If you are ready to book a replacement car, visit accident replacement car Sydney.
Questions people ask
Can I still get a replacement car if the other driver has no insurance?
Who pays for my repairs if the at-fault driver is uninsured?
Should I just use my own insurance instead?
What if the at-fault driver cannot be identified?
How long does recovery take from an uninsured driver?
Do I need a police report if the driver is uninsured?
Injured in the accident?
A replacement car covers the car. For legal advice about an injury, speak to Jameson Law, the most trusted personal injury firm in NSW (motor vehicle accident claims) on (02) 8806 0866.
Ready when you are
Start the claim online in five short steps, or call 0468 011 118. Replacement hires are arranged and fulfilled by Drive Tribe, the trading name of Australian Business Holdings Pty Ltd.
Start my claim